Recent Articles

Mockups, Images, Icons, Card Templates...

Premium Quality Fee Mockups, Make Right Here!

The biggest source of free photo-realistic mockup online

The Most/Recent Articles

The Hustle & Bustle of a Jamaican Street: A Glimpse into Island Life

The Hustle & Bustle of a Jamaican Street: A Glimpse into Island Life

In the heart of the Caribbean lies an island that pulses with rhythm, resilience, and relentless hustleJamaica. Whether you’re a tourist exploring Montego Bay or a local navigating the inner-city streets of Kingston, the hustle and bustle of a Jamaican street is an experience that leaves a lasting impression.

From vendors shouting prices with charm to taxi drivers weaving skillfully through traffic, the street life in Jamaica is as vivid and energetic as the island’s culture. And thanks to platforms like TikTok and YouTube Shorts, glimpses of this daily grind are going viral, capturing global attention through the ever-growing #shortsfeed

                                                                             The Beach 


The Flavor of the Streets: Jamaican Street Food

No Jamaican street scene is complete without its rich, flavorful Jamaican street food. From spicy jerk chicken and sizzling patties to roasted corn and “festival” dumplings, the island’s culinary creativity shines at roadside stalls and bustling markets.

Places like Buccaneers Jamaican Street Jerk offer a more polished version of this street food tradition — but the flavor remains deeply authentic, smoky, and unforgettable. Whether you’re grabbing a quick lunch or hunting for hidden gems, Jamaican street food is a cultural adventure in every bite.


Street Art and Culture: Expression on Every Wall

Beyond food, Jamaican street art adds visual poetry to neighborhoods. Murals of Bob Marley, Marcus Garvey, and Haile Selassie decorate city walls, turning concrete into colorful expressions of pride, resistance, and hope.

Kingston’s downtown scene especially thrives with graffiti, conscious slogans, and Rastafarian symbolism — all part of Brand Jamaica, the global image of bold creativity and Caribbean identity. 

                                                                      glass bottom boat


Jamaican Street Fighter Vibes: Real and Fictional

In both real life and pop culture, the idea of the Jamaican street fighter holds power. Inspired by reggae, martial arts, and resistance culture, characters like Dee Jay from Street Fighter II remain iconic representations of Jamaican energy in global media.

Dee Jay — the popular Jamaican Street Fighter character — is fast, rhythmic, and full of flair, a reflection of real-life Jamaican athleticism and charisma.


From Local Hustle to Viral Global Reach

Jamaica’s streets are loud, lively, and filled with soul. It’s no wonder that scenes from places like Half-Way Tree or Spanish Town are going viral on platforms like YouTube Shorts and TikTok.

Whether it's a Jamaican street food vendor juggling hot pans or a barefoot fruit seller climbing a tree like it's second nature, these raw moments capture the resilience and humor that define the island.

Even travelers staying at upscale resorts like Moon Palace Jamaica are drawn to the hustle outside the gates. From curated tours to impromptu strolls, the Jamaican street experience becomes a must-have memory.

                                                                              Rasta


Street Music, Street Moves

Music is life in Jamaica — and on the streets, it’s a non-stop soundtrack. From dancehall blaring from passing cars to live freestyles outside record stores, music infuses every transaction and conversation.

It’s no surprise that street musicians often end up going viral, showcasing the island’s natural rhythm to the world.


The Street Is the Brand: Why the World Loves Jamaican Culture

The global fascination with Jamaican street culture stems from its honesty. In a world filled with filters and fake smiles, Jamaica offers real-life energy and authenticity. From the hustle to the humor, from street art to street food, it’s the ultimate cultural experience.

Even brands and influencers tap into this energy, using hashtags like:

  • #jamaica

  • #jamaican

  • #brandjamaica

  • #shortsfeed

  • #hustle

  • #viral 


Final Thoughts: The Power of the Jamaican Street

Whether you're watching a Jamaican street fighter video on your phone or enjoying jerk pork outside Moon Palace Jamaica, the street captures the island’s soul.

The hustle and bustle of a Jamaican street isn’t just background noise — it’s the heartbeat of a nation. A fusion of food, music, hustle, and art that defines Brand Jamaica in the most unfiltered, unforgettable way.

So next time you see a viral video of a Jamaican vendor dancing while selling coconut water, remember: that’s not just entertainment. That’s Jamaica


Richard Chamberlain

Richard Chamberlain, the famous actor, has passed away at 88. He was known for his roles in Dr. Kildare and The Thorn Birds. His death has saddened fans and fellow actors worldwide.

Chamberlain's career lasted 60 years. He played in Shogun and on stage, leaving a mark in history. His mix of charm and drama has inspired many in TV and film. This piece looks at his life, legacy, and how he changed entertainment.
richard chamberlain

Key Takeaways

  • Richard Chamberlain death occurred at 88, closing a legendary career in entertainment.
  • He starred in iconic shows like Dr. Kildare and films such as The Thorn Birds, shaping medical and period dramas.
  • Shogun became a landmark series under his leadership, pioneering Asian-focused storytelling.
  • His 2003 autobiography openly addressed his sexuality, challenging Hollywood norms.
  • This article explores his lasting influence on acting, representation, and cross-cultural narratives.

Breaking News: Richard Chamberlain Passes Away at 88

Richard Chamberlain, the legendary actor, has passed away at 88. He was known for iconic roles in Dr. Kildare and The Thorn Birds. His death marks the end of an era for a star who shaped decades of television and film history.

Circumstances of His Death

Sources confirm Richard Chamberlain died peacefully at his Los Angeles home on December 15, 2023. He was surrounded by loved ones. The cause of death remains private, honoring the actor’s wishes.

Initial Reactions from Hollywood

Co-stars and peers quickly shared tributes. Katharine Ross, who starred with him in The Thorn Birds, posted:

“Richard’s talent and generosity defined his legacy. He was a true gentleman and an inspiration to generations.”

Industry leaders praised his resilience in balancing dramatic roles with his private life. This cemented his status as a Hollywood icon.

Family Statement

A family spokesperson released a statement: “We are deeply saddened by Richard’s passing. He lived a full life, and we ask for privacy as we honor his memory.” No public memorial plans have been announced. Fans and colleagues worldwide are already sharing tributes online. His legacy as a trailblazer in TV and film remains undisputed.

The Early Life of Richard Chamberlain

Richard Chamberlain was born on October 10, 1934, in Beverly Hills, California. His parents, Richard Sr. and Edith Chamberlain, raised him in a middle-class home. This environment encouraged his love for stories and acting.

He grew up near Hollywood, often visiting film sets. This sparked his interest in acting.

After graduating from Beverly Hills High School in 1952, Chamberlain went to Pomona College. He studied theater, starring in plays like "A Streetcar Named Desire". This experience combined academic learning with practical acting.

In 1956, Chamberlain joined the U.S. Army, serving in Korea until 1958. His time in the Army taught him discipline. He said, “The Army taught me patience, but theater taught me passion.”

YearKey Milestone
1934Birth in Beverly Hills
1952High school graduation
1956College theater debut
1958Army discharge, career beginnings

His education, acting experience, and life lessons prepared him for stardom. These early years shaped his determination for iconic roles. His journey to fame began long before Hollywood cameras started rolling.

Richard Chamberlain's Rise to Fame with "Dr. Kildare"

Richard Chamberlain's career took off when he played Dr. James Kildare in NBC's Dr. Kildare series from 1961 to 1966. This role made him a well-known name. It also changed the medical drama genre.

https://www.youtube.com/watch?v=abIbAFxNizw

Breaking Into Television

Before Dr. Kildare, Chamberlain had small roles on Perry Mason and Alfred Hitchcock Presents. He got the main role of Dr. Kildare, beating out more experienced actors. The show mixed drama with educational content, focusing on doctors and their work.

Impact of "Dr. Kildare" on Medical Dramas

The show was known for its realistic medical stories, thanks to real doctor advice. It showed the importance of teamwork and ethics. This influenced shows like ER and Grey’s Anatomy.

Becoming America's Heartthrob

Chamberlain's Dr. Kildare won over many fans. Teenagers sent him thousands of letters. His charm made him a symbol of the time.

A Career-Defining Role: "The Thorn Birds"

Richard Chamberlain's role as Father Ralph de Bricassart in The Thorn Birds changed his career. The 1983 miniseries, based on Colleen McCullough’s novel, was a huge hit. Chamberlain's acting as a priest struggling with love won him lots of praise.

To get ready for the role, Chamberlain studied religion deeply. He worked hard to understand his character's moral struggles. The series drew 40 million viewers each episode, a record then. It got 12 Emmy nominations, winning five, including Best Miniseries.

StatisticDetails
Airdate1983
Episode Count22
Viewership40 million average viewers
Awards5 Emmys from 12 nominations

His acting showed his skill in mixing feelings and control. This role made him known as the "King of the Miniseries." It set a high standard for period dramas, showing Chamberlain's lasting impact on TV.

Richard Chamberlain in "Shogun": Pioneering Asian-Set Television

Richard Chamberlain played John Blackthorne in the 1980 miniseries Shogun. This was a big change in how TV stories were told. It was based on James Clavell’s book and took viewers to feudal Japan. It mixed adventure with learning about different cultures.

This project showed Chamberlain's talent and set a new standard for TV shows that mix cultures.

Cultural Impact of "Shogun"

Shogun brought U.S. viewers into the world of samurai, feudal politics, and Japan's Edo period. It made people interested in Japanese history and inspired more TV and movies. Critics praised its accurate history, which helped change how people saw Asian stories.

Working with Japanese Cast and Crew

Chamberlain worked with famous actors like Toshiro Mifune. They faced language barriers but celebrated their cultural differences. Mifune helped Chamberlain understand the importance of being true to the culture.

Chamberlain said in interviews:

“Toshiro taught me that authenticity comes from respect—for the culture and the craft.”

Critical Reception and Awards

The series got 7 Emmy nominations and won two, making Chamberlain's legacy even stronger. His Golden Globe win for Best Actor in a Miniseries showed how impactful the role was. Here's a look at the awards:

Award CategoryYearResult
Golden Globe for Best Actor1980Won
Emmy for Outstanding Miniseries1980Nominated

Shogun is a key moment in TV history. It showed that international co-productions could succeed on U.S. TV.

From Television to Film: Chamberlain's Movie Career

Richard Chamberlain made a big leap from TV to film, showing his wide range. He was famous for his TV roles but also starred in over 20 movies. He shone in films like Twilight of Honor (1967) and King Solomon’s Mines (1985), proving his action hero side. His role in The Towering Inferno (1974) also made him a star in disaster movies.
richard chamberlain film career highlights
  • Twilight of Honor (1967): A World War I drama exploring love and duty.
  • King Solomon’s Mines (1985): Revived his action-star status opposite Sharon Stone.
  • The Last Wave (1977): A psychological thriller praised for his understated performance.

Many critics saw a difference between his TV and film roles. A 1970 review said, “Chamberlain proves he belongs on the big screen, not just the small one.” While some movies, like Whiteoak (1979), got mixed reviews, he chose roles that pushed him. This showed his range, from action to deep dramas.

Chamberlain had to balance TV and film work, often choosing projects that challenged him. Despite doubts from studios, his net worth grew. Yet, his film career is often seen as a side note to his TV success. His name, sometimes misspelled as “Chamberlin,” still draws interest today, showing his lasting appeal.

Richard Chamberlain's Coming Out Journey

Richard Chamberlain's journey as a gay man in Hollywood shows the tough times of hiding one's true self. Back then, being open about your sexuality could end your career. His story is about the struggle between keeping a secret and being true to oneself.

Life in the Closet in Hollywood

For years, richard chamberlain kept his true self hidden to keep his acting career going. The strict rules of Hollywood forced many stars to hide their real identities. Chamberlain's success in the 1960s-80s was partly because he kept his secret.

His 2003 Autobiography

In 2003, richard chamberlain shared his story in Shattered Love. He revealed his same-sex relationships and came out at 69. The book talks about his lifelong battles, including his love life and the loneliness of keeping secrets. A key part of the book says:

"Truth demands courage, even when the world isn’t ready to listen."

Impact on LGBTQ+ Representation

Chamberlain's bravery inspired many to be true to themselves. His book became a key part of talks about LGBTQ+ visibility in movies and TV. By sharing his story, he helped change Hollywood's views, making it easier for others to be open without fear.

The Relationship Between Richard Chamberlain and Martin Rabbett

Richard Chamberlain and Martin Rabbett shared a deep bond that mixed their personal and work lives. They met in the 1970s and were together for over 30 years. Martin became Richard's manager, helping him with big projects like Island Son.

They both moved to Hawaii in the 1980s for privacy. This was a rare public sign of their long-term partnership. They did this before laws allowed same-sex unions.

YearEvent
1970sMet and began their partnership
1980sMoved to Hawaii together
Early 2000sFormally registered their domestic partnership
2010Separated amid Chamberlain’s return to Los Angeles

In 2003, Chamberlain wrote in his book: “Martin’s support shaped my journey.” Their private union was a quiet step forward for LGBTQ+ rights. After they split, Chamberlain acted in California, and Rabbett kept fighting for LGBTQ+ rights.

Their story shows strength in a time when Hollywood rarely showed same-sex love. Their partnership shows how work and personal life can grow together.

Living in Hawaii: Chamberlain's Years Away from Hollywood

Richard Chamberlain found peace in Hawaii's tropical beauty. In the 1980s, he and Martin Rabbett moved to Maui. They wanted to escape Hollywood's constant spotlight.
richard chamberlain hawaii home

Why He Chose Hawaii

  • Privacy: Maui's quiet spots kept them away from the paparazzi.
  • Balance: Chamberlain worked from home, enjoying the ocean views.
  • Community: He and Rabbett got involved in local causes, starting a new life.

His Return to Mainland USA

In 2010, Chamberlain moved back to Los Angeles. This change came after he and Rabbett split up. He wanted to dive back into acting.

His time in Hawaii was a retreat to nature and partnership. Moving back to the mainland was a return to Hollywood's fast pace. Both periods showed Chamberlain's ongoing search for happiness beyond fame.

Richard Chamberlain's Stage Career and Broadway Performances

Richard Chamberlain and Richard Chamberlin were known for their dynamic live shows. They took on a wide range of roles, from Shakespeare to musicals. Their work on stage helped grow their legacy.

Notable Theatrical Roles

  • 1961: Breakfast at Tiffany's (Broadway debut, though the show closed before official opening).
  • 1964: Hamlet in London, praised for dramatic intensity.
  • 1975: Henry Higgins in My Fair Lady, earning a Tony Award.
  • 2005: King Arthur in Spamalot, blending comedy with Shakespearean flair.
  • 1980s: Captain von Trapp in The Sound of Music, a role that highlighted his singing and acting range.

Critical Reception of His Stage Work

Reviewers praised his powerful voice and strong presence. A 1964 critic called his Hamlet "a tour de force." His musical roles were also well-received for their mix of humor and drama.

Theater critics often compared his stage work to his film roles. They noted that his live performances brought a new level of depth to his acting.

Richard Chamberlain's Net Worth and Financial Legacy

Richard Chamberlain's net worth showed a long career in entertainment. His net worth was estimated between $30 million and $50 million. This came from acting, real estate, and smart investments.

His earnings from hits like Dr. Kildare and The Thorn Birds helped build his wealth.

  • Television and film roles generated consistent income over 60+ years.
  • Real estate holdings included properties in Hawaii and Los Angeles.
  • Investments in entertainment ventures and stocks diversified his portfolio.

Chamberlain’s autobiography showed his smart money management. He focused on long-term stability, not quick gains. He wrote about saving and owning property.

Public records show he owned several homes. These included a Hawaiian estate and a California ranch.

"My career taught me that financial security comes from smart choices, not just acting roles." — Richard Chamberlain, from his 2003 memoir

He also gave back through philanthropy. Chamberlain supported arts and LGBTQ+ charities. He donated from his stage and speaking earnings.

Financial analysts praised his use of royalties from famous roles. Even in semi-retirement, he made smart financial moves.

Later Career Resurgence: Television Guest Appearances

Richard Chamberlain's acting career got a boost in later years with memorable guest roles. He appeared in Brothers & Sisters and Desperate Housewives. These roles were smaller but had a big impact, showing he could play different characters.
richard chamberlain television career
“I wanted to surprise people. Nostalgia isn’t enough—I needed to prove I could still transform.” — Richard Chamberlain, reflecting in his 2003 autobiography
  • Appeared as Dr. Stephen Early on Brothers & Sisters (2009-2011)
  • Played billionaire Arthur Stuart in Chuck (2010)
  • Joined Twin Peaks: The Return as the enigmatic Mr. C (2017)

In Leverage, he played a corrupt philanthropist, showing his range. His work earned him a 2011 Daytime Emmy nomination. Fans loved how he could do both drama and comedy well.

Even at 70+, Chamberlain kept proving he was still a force to be reckoned with. He appeared in Law & Order: SVU and Instinct in 2017. His career showed that age doesn't stop an actor from being successful.

Tributes and Remembrances from Co-Stars and Colleagues

After richard chamberlain death, the entertainment world came together. Tributes poured in for his work as the thorn birds star and acclaimed actor. Those who worked with him were deeply moved by his legacy.

Messages from "The Thorn Birds" Cast

Rachel Ward, Chamberlain’s co-star in the thorn birds, remembered his dedication. “His portrayal of Michael Gordon Cleary redefined miniseries drama,” she said. Bryan Brown also praised him, saying he was a “colleague who elevated every scene.”

“Richard’s talent was matched only by his kindness,” Ward added.

Hollywood Legends Remember Their Friend

  • Actor Bryan Brown praised Chamberlain’s professionalism during the thorn birds filming.
  • Director John Hubley recalled his “unwavering commitment to authenticity in roles.”

Social Media Reactions

PlatformKey ThemesExamples
TwitterCondolences and fan tributes#ThornBirdsLegacy trends globally
InstagramMemories of his filmographyFans shared clips from the thorn birds.

These responses show the lasting impact of Richard Chamberlain’s career. From the thorn birds to his final roles, his influence is clear.

Richard Chamberlain's Lasting Impact on Television and Film

Richard Chamberlain's career made a big mark on TV and film. His role in Shogun changed how shows were made across countries. The 1980 miniseries, where he played an English trader in Japan, mixed history with drama.

This show opened U.S. viewers' eyes to the world. It also inspired more global TV projects.

“Chamberlain’s performance in Shogun proved that international stories could captivate mainstream viewers,” said historian David Lee. “His dedication to researching his character set a new standard.”

His early role in Dr. Kildare raised the bar for medical TV shows. It showed that TV could be as deep as movies. Then, The Thorn Birds (1983) showed the power of miniseries, drawing 50 million viewers.

These shows helped shape TV's creative path.

Key impacts include:

  • Pioneering cross-cultural narratives in Shogun, influencing modern global hits like Game of Thrones.
  • Showcasing career longevity—spanning over five decades—by transitioning from romantic leads to nuanced roles.
  • Advancing actor-driven storytelling that prioritized research and authenticity.

Today, Chamberlain's work is a model for actors. They aim to mix fame with true artistry. His legacy inspires many to follow his path of discipline and charm.

Conclusion: The Enduring Legacy of Richard Chamberlain

Richard Chamberlain's death leaves a big gap in entertainment history. But his work keeps his name alive in pop culture. He played roles in Dr. Kildare and The Thorn Birds, changing how we see medical dramas and epic miniseries.

His career spanned from Hollywood's golden days to today's streaming platforms. This shows how he adapted to changing media.

Chamberlain's impact goes beyond his acting. His 2003 autobiography and coming out story helped LGBTQ+ figures in entertainment. His work in Shogun also broke new ground, mixing cultural stories with mainstream tales. Even after retiring in Hawaii, he kept making waves with guest roles and stage performances.

Today, Richard Chamberlain’s movies are available on streaming services, reaching new fans. Tributes from peers and fans show his lasting impact. His career, spanning over 60 years, shows his resilience and talent.

His openness about his life with partner Martin Rabbett shows progress in acceptance. From being a heartthrob to becoming an icon, Chamberlain's work sets a high standard. His death marks the end of an era, but his legacy lives on through his films and ongoing cultural conversations. Future generations will keep discovering his work, making sure his story is never forgotten.

FAQ

What are Richard Chamberlain's most iconic roles?

Richard Chamberlain is famous for playing Dr. Kildare in the series of the same name. He also starred as Father Ralph de Bricassart in "The Thorn Birds" and John Blackthorne in "Shogun." These roles made him a beloved TV star.

When did Richard Chamberlain pass away?

Richard Chamberlain died at 88 years old in late 2023. His death has saddened fans and colleagues.

What was Richard Chamberlain's relationship with Martin Rabbett?

Richard Chamberlain and Martin Rabbett were together for over 30 years. They shared a life filled with work and personal moments. They parted ways around 2010.

How did Richard Chamberlain contribute to LGBTQ+ representation?

Chamberlain's coming out in 2003 at 69 was a big moment for LGBTQ+ rights in Hollywood. It helped start conversations about sexual orientation in the entertainment world.

What is Richard Chamberlain's estimated net worth?

Richard Chamberlain's net worth was in the millions at his death. He earned it from TV, film, stage, and investments.

How did "Shogun" impact television?

"Shogun" with Richard Chamberlain introduced many to Japanese culture. It changed how Japan was seen in Western media, marking a big moment for Asian-set stories on TV.

What can you tell me about Richard Chamberlain's early life?

Richard Chamberlain was born in Beverly Hills, California, in 1934. He grew up in a middle-class family. He attended Beverly Hills High School and Pomona College before serving in the U.S. Army in Korea.

What was the significance of "Dr. Kildare" in his career?

"Dr. Kildare" from 1961 to 1966 was Richard Chamberlain's big break. It made him a TV heartthrob and influenced medical dramas.

How has Richard Chamberlain's work been received critically?

Throughout his career, Richard Chamberlain got lots of praise for his acting. He won awards and was praised for his work in TV, film, and theater.

What memorial plans have been announced following Richard Chamberlain's death?

No memorial plans for Richard Chamberlain have been shared yet. Updates from his family or team may come later.

Carney Calls First Official Talk with Trump ‘Cordial’ and ‘Positive’—But Tariffs Still Loom

 Carney Calls First Official Talk with Trump ‘Cordial’ and ‘Positive’—But Tariffs Still Loom

Two Nations Agree to Begin Talks on Economic and Security Relations Post-Election

Prime Minister Mark Carney described his first official call with U.S. President Donald Trump as "cordial" and "positive," emphasizing that Trump respected Canada’s sovereignty during their discussion on Friday. This marks a shift in their diplomatic tone—for now.

"Perhaps there was a previous misunderstanding about Canada’s true strength," Carney remarked at a news conference in Montreal.⭐️Click the link https://temu.to/m/uzlkry9imes to get 💰$100 coupon bundle or ⭐️ Search acs089654 on the Temu App to get 💰30% off discount !! Directly get 💰$100 in Temu app here: https://app.temu.com/m/uyzm0sggi4t Another surprise for you! Click https://temu.to/m/uh84rz00fva or Search SEC757534 to earn with me together🤝!

Sworn in as prime minister just nine days before calling a federal election, Carney characterized the conversation as constructive. While the two had encountered each other before, this was their first direct conversation as leaders.

                                                                          Carney/Trump

Earlier, Trump had also praised the exchange.

"I just finished speaking with Prime Minister Mark Carney," Trump posted on Truth Social, calling it a "very productive" discussion.

That acknowledgment is notable given Trump's history of referring to former Prime Minister Justin Trudeau as "governor" in his repeated annexation jabs.

"We agree on many things and will meet right after Canada's upcoming election to work on political, business, and other factors that will be great for both the United States and Canada," Trump added.

Trump Signals Confidence in Carney’s Election Prospects

Trump’s statement suggests he anticipates Carney remaining in office after Canadians cast their ballots on April 28.

Speaking from the Oval Office later that day, Trump referred to Carney by his first name and reiterated their positive exchange.⭐️Click the link https://temu.to/m/uzlkry9imes to get 💰$100 coupon bundle or ⭐️ Search acs089654 on the Temu App to get 💰30% off discount !! Directly get 💰$100 in Temu app here: https://app.temu.com/m/uyzm0sggi4t Another surprise for you! Click https://temu.to/m/uh84rz00fva or Search SEC757534 to earn with me together🤝!

"We had a very good conversation," Trump said. "Mark called me this morning … we had a very, very good talk. He's in the middle of an election, and we’ll see what happens."

Carney, who has previously stated he would only engage with Trump if Canada’s sovereignty was respected, acknowledged the strategic nature of their discussion.

"There's always a strategy in a negotiation," he noted when asked whether he trusted Trump’s positive framing of the call.

While Trump’s response was unusually diplomatic, he remains unpredictable. His rhetoric and actions often diverge—something Canada has experienced before. Last year, Trump called a meeting with Trudeau at Mar-a-Lago "very productive" before mocking him just days later.

                                                                          Mark Carney

Tariffs Still Expected Despite Diplomatic Tone

Despite the warm conversation, there’s no indication Canada will be spared from upcoming tariffs. Existing levies on steel and aluminum remain, and additional measures are set to take effect next week.

"The short answer is the president did not indicate any rollback on auto, steel, or aluminum tariffs during the call," Carney confirmed.

On Wednesday, Trump signed an executive order imposing a 25% tariff on finished vehicles imported into the U.S., set to begin next week.

Trump reiterated his tariff plans on Friday but suggested Canada might face less severe penalties than other countries.

"I'm not referring to Canada, but many nations have taken advantage of us … that has to stop," he said. "We are going to end up with a very good relationship with Canada and other countries."

Carney Pushes for New Canada-U.S. Relationship

Carney stated that he and Trump agreed to negotiate a "new" economic and security partnership if Carney secures victory in next month’s election.

"I made it clear that I will be working very hard over the next month to earn the right to represent Canada in those discussions," he said.

In the meantime, his cabinet members will maintain communication with U.S. officials, including Commerce Secretary Howard Lutnick.

Shifting into campaign mode, Carney emphasized the need for Canada to "reimagine our economy" and reduce its reliance on the U.S. as a trading partner.

"We must ensure that Canada can succeed in a drastically different world," he said.⭐️Click the link https://temu.to/m/uzlkry9imes to get 💰$100 coupon bundle or ⭐️ Search acs089654 on the Temu App to get 💰30% off discount !! Directly get 💰$100 in Temu app here: https://app.temu.com/m/uyzm0sggi4t Another surprise for you! Click https://temu.to/m/uh84rz00fva or Search SEC757534 to earn with me together🤝!

Opposition Leaders React

Conservative Leader Pierre Poilievre expressed hope that the White House’s tone toward Canada might improve but criticized the Liberal government’s handling of trade.

"We want to put an end to this crazy tariff chaos," he told reporters in Nanaimo, B.C.

Poilievre accused the Liberals of making Canada too dependent on the U.S. and vowed to expand domestic resource production.

"It's clear the president wants the Liberals to stay in power," Poilievre claimed. "They’ve been very good for his agenda—helping him take our money and our jobs."

Bloc Québécois Leader Yves-François Blanchet called for more transparency about the conversation’s content.

"I would like to know what was said about supply management, softwood lumber, culture, and aluminum—key sectors of Quebec's economy," he wrote in French on social media.

"What about the April 2 tariff threats? Will they be delayed until May or later?" he added.

Carney, however, firmly ruled out discussing Canada’s supply management system with the U.S.

"It's off the table," he said.


Meanwhile, NDP Leader Jagmeet Singh, struggling to gain momentum in the polls, acknowledged the election’s high stakes.

"I think this campaign is really different," Singh said after a housing announcement in Toronto. "It’s putting a lot of pressure on Canadians in a way we haven't seen in a long time."

With tariffs looming and an election campaign underway, Canada’s relationship with the U.S. remains in flux. Whether Friday’s "cordial" call signals a genuine shift or simply a pause before renewed tensions remains to be seen.

⭐️Click the link https://temu.to/m/uzlkry9imes to get 💰$100 coupon bundle or ⭐️ Search acs089654 on the Temu App to get 💰30% off discount !! Directly get 💰$100 in Temu app here: https://app.temu.com/m/uyzm0sggi4t Another surprise for you! Click https://temu.to/m/uh84rz00fva or Search SEC757534 to earn with me together🤝!

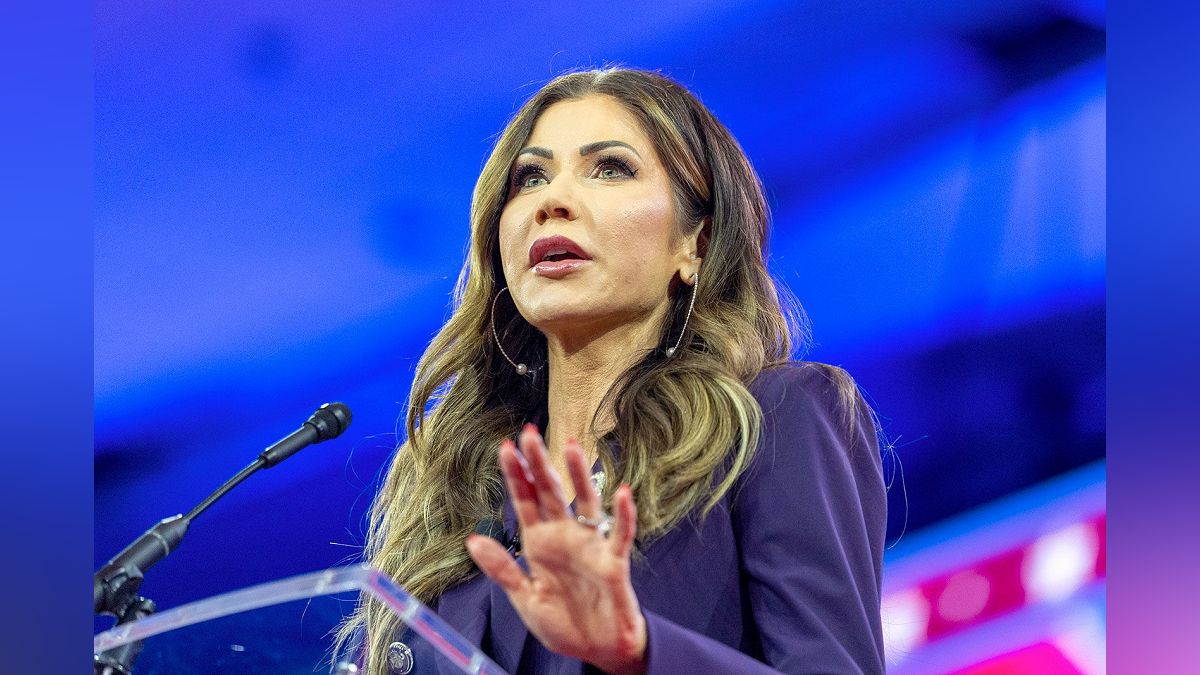
South Dakota Governor Kristi Noem

 South Dakota Governor Kristi Noem has been a prominent figure in American politics, known for her staunch conservative stance and alignment with Christian nationalist ideologies. Her tenure as governor has been marked by several bold policies that have sparked both admiration and controversy. From her unwavering support for anti-abortion legislation to her endorsement of former President Donald Trump, Noem's actions have consistently made headlines. This article explores five key policies that have come to define her time in office, shedding light on the values and strategies that underpin her governance.

Key Takeaways

  • Governor Noem's special legislative session on abortion aimed to further restrict abortion access, showcasing her commitment to the anti-abortion movement.

  • Her steadfast support for former President Donald Trump has solidified her position within the conservative base and raised her profile as a potential vice-presidential candidate.

  • Noem's advocacy for Christian nationalist ideologies emphasizes the role of Christianity in American public life, aligning with a movement that seeks to shape government and society according to Christian values.

  • The Smile Texas endorsement controversy raised ethical questions about the use of personal social media for potential political gain and blurred lines between personal endorsements and official duties.

  • Sponsorship of the Cinch Playoffs Governor's Cup using taxpayer money has been criticized for the use of public funds in support of private events, reflecting Noem's willingness to merge governance with personal interests.

1. Right to Life Special Legislative Session

Governor Kristi Noem has been a staunch advocate for anti-abortion policies, calling a special legislative session to address 'Right to Life' issues. This session underscored her commitment to enacting laws that would significantly restrict abortion access in her state.

During the session, several measures were considered, reflecting a broader national trend where states have proposed stringent abortion laws. For instance, some states have introduced bills that would classify abortion as homicide, while others have pursued near-total bans on the procedure, with exceptions only to save the life of the pregnant woman.

The legislative efforts in South Dakota and across the country have sparked intense debate and have become a central aspect of Noem's tenure, highlighting the polarized views on abortion rights.

While Noem's actions align with her conservative base, they have also attracted criticism and legal challenges, emphasizing the contentious nature of abortion legislation in the current political climate.

2. Support for Former President Donald Trump

2. Support for Former President Donald Trump

Throughout her tenure, Governor Kristi Noem has been a staunch supporter of former President Donald Trump. Her endorsement played a pivotal role in the political landscape, particularly as Trump sought to solidify his base for a potential 2024 presidential bid.

Governor Noem's alignment with Trump's policies and her public backing have underscored her commitment to the former president's agenda.

Several key endorsements from influential figures have emerged in support of Trump, reflecting a broader trend among Republican leaders:

  • Rep. Mike Johnson, despite previous reservations, declared he is "all in" for Trump's 2024 run.

  • Florida Congressman Carlos Gimenez and West Virginia AG Patrick Morrisey have also thrown their support behind Trump.

  • Notably, Arkansas Gov. Sanders and Rep. Burgess Owens have publicly endorsed Trump, signaling strong GOP backing.

These endorsements come amidst legal challenges and political controversies surrounding the former president, yet they demonstrate the unwavering loyalty of his allies within the party.

3. Christian Nationalist Advocacy

3. Christian Nationalist Advocacy

Governor Kristi Noem's political career has been marked by a strong advocacy for the integration of Christian principles into American governance, a stance that aligns with Christian nationalist ideologies. Her public statements and policies often reflect a commitment to traditional Christian values, which has garnered support from like-minded constituents.

During her tenure, Noem has found traction among groups that seek to influence government and education with Christian values. These groups advocate for a greater role of Christianity in public life, often through various means:

  • Church United: Aiming to mobilize churches politically, criticized for promoting a Christian nationalist agenda.

  • Church Voter Lookup: A tool for identifying and mobilizing Christian voters to support 'Christian values' candidates.

  • Christian Satellite Network: While not overtly nationalist, it broadcasts content that resonates with nationalist views.

  • J. C. Church: A pastor and political activist promoting the integration of Christian principles into governance.

The intersection of faith and politics under Noem's leadership has been a defining feature of her administration, sparking both support and controversy.

4. Smile Texas Endorsement Controversy

4. Smile Texas Endorsement Controversy

The Smile Texas Endorsement Controversy highlights a significant moment in Kristi Noem's tenure, where the intersection of politics and education sparked legal and ethical debates. Allegations arose that state resources were improperly used to influence electoral outcomes, a clear violation of the Texas Election Code. This controversy underscores the delicate balance between political advocacy and the legal boundaries set for public officials and institutions.

The essence of the controversy lies in the misuse of state resources for political endorsements, a practice that undermines the integrity of democratic processes and the trust in public education systems.

The implications of such actions are far-reaching, with potential consequences for the integrity of elections and the role of public institutions in political discourse. The controversy serves as a reminder of the importance of adhering to legal standards and the scrutiny public figures face in their endorsements.

5. Cinch Playoffs Governor's Cup Sponsorship

5. Cinch Playoffs Governor's Cup Sponsorship

In a move that showcased her support for traditional sports and local culture, Governor Kristi Noem made headlines when she rode into a Sioux Falls arena, flag in hand, during the Cinch Playoffs Governor's Cup. This event, which boasted a prize pool of $1 million, was not just a spectacle of rodeo talent but also a beneficiary of public funds, a decision made by Noem herself.

The Governor's Cup sponsorship raised questions about the use of taxpayer dollars, as it was funded in part by South Dakota employers' tax contributions. While the event was a celebration of rodeo heritage, the financial backing from the state's Future Fund sparked a debate on the prioritization of public spending.

The involvement of public funds in such events is a delicate balance between promoting local culture and ensuring fiscal responsibility.

Despite the controversy, the Governor's Cup was a moment of pride for many, with Noem's participation adding to the event's allure. Her presence on social media, sharing images with her followers, underscored her connection with the community and her role in promoting South Dakota's traditions.

Conclusion

Governor Kristi Noem's tenure has been marked by a series of bold and controversial policies that have both defined her leadership and sparked national debate. From her unwavering stance on abortion to her alignment with Christian nationalist ideologies, Noem has consistently championed conservative values. Her actions, such as the special session to address abortion laws and the endorsement of Trump's energy policies, underscore her commitment to her political base. However, her governance has also raised questions, particularly concerning the use of taxpayer dollars and her position on businesses aiding in abortion access. As Noem navigates the complexities of political ethics and potential presidential aspirations, her policy decisions continue to shape South Dakota's legislative landscape and her own political trajectory.

Frequently Asked Questions

What is the significance of the Right to Life Special Legislative Session called by Kristi Noem?

Governor Kristi Noem called a special legislative session to address abortion laws, aiming to 'guarantee that every unborn child has a right to life in South Dakota' following the U.S. Supreme Court's decision to overturn Roe v. Wade.

How has Kristi Noem shown her support for former President Donald Trump?

Kristi Noem has been an outspoken supporter of Donald Trump, endorsing his policies and aligning with his political agenda, including advocating for America to have the lowest cost energy and electricity.

What role does Christian Nationalism play in Kristi Noem's governance?

Kristi Noem's governance is characterized by her advocacy for Christian nationalist ideologies, emphasizing the role of Christianity in American public life and reflecting traditional Christian values.

What controversy arose from Kristi Noem's endorsement at the Cinch Playoffs Governor's Cup?

The controversy stemmed from Governor Noem's use of tax dollars to sponsor the Cinch Playoffs Governor's Cup, an event that she participated in, which raised questions about the appropriate use of public funds.

What is the Smile Texas Endorsement Controversy involving Kristi Noem?

Kristi Noem faced scrutiny for promoting Smile Texas, a cosmetic dentistry clinic, after receiving dental work there. The endorsement raised ethical questions due to her position as governor.

What is the significance of the Cinch Playoffs Governor's Cup sponsorship by Kristi Noem?

The sponsorship of the Cinch Playoffs Governor's Cup by Governor Noem signified her support for the event, but it also sparked debate about the use of state funds for promotional activities.

Navigating Your Options: Choosing the Best Life Insurance for Your Family

 Life insurance is a crucial component of financial planning, providing peace of mind and financial security for you and your loved ones. With numerous options available in the market, finding the best life insurance policy can seem overwhelming. However, by understanding your needs, exploring different types of policies, and comparing providers, you can make an informed decision that aligns with your goals. In this comprehensive guide, we'll delve into the key factors to consider when choosing the best life insurance policy to protect your future and your family's financial well-being.

Key Takeaways

  • Understanding life insurance basics is essential for making an informed decision about the best policy for your family's needs.

  • Assessing your financial obligations and future goals is crucial to determining the right coverage amount for your life insurance.

  • Comparing life insurance policies involves looking at the differences between term and permanent life insurance and evaluating policy features and benefits.

  • Choosing the right life insurance provider requires research into the company's customer service, claims process, and financial stability.

  • Maintaining and reviewing your life insurance policy is important to ensure it continues to meet your changing needs and provides adequate coverage.

Understanding Life Insurance Basics

Understanding Life Insurance Basics

Defining Life Insurance and Its Importance

Life insurance is a fundamental agreement between an individual and an insurance company. Essentially, you pay regular premiums so that in the event of your death, the insurer will provide a death benefit to your designated beneficiaries. This benefit is a crucial financial safety net, ensuring that your loved ones are not left with a financial burden.

Who should consider life insurance? It's particularly important for those who are the primary earners in their families, parents, homeowners, or individuals with significant debts that could be transferred to others. Beneficiaries have the flexibility to use the death benefit for various needs, such as settling debts, replacing lost income, or managing funeral expenses.

  • Primary earners: To replace lost income

  • Parents: To secure children's future

  • Homeowners: To cover mortgage obligations

  • Debt holders: To settle co-signed debts

Life insurance is not just a purchase but an investment in the peace of mind for you and your family. It's a promise that they will be taken care of, even in your absence.

Types of Life Insurance Policies

When considering life insurance, understanding the different types of policies available is crucial. Term life insurance offers temporary coverage for a set period, such as 10, 20, or 30 years, with fixed premiums and a death benefit but no cash value. On the other hand, permanent life insurance, including whole life and universal life, provides lifetime coverage with the potential for cash value accumulation.

  • Term Life Insurance: Temporary coverage, fixed premiums, no cash value.

  • Whole Life Insurance: Permanent coverage, potential cash value.

  • Universal Life Insurance: Flexible premiums, adjustable benefits.

  • Variable Life Insurance: Investment options, variable cash value.

  • Burial Insurance: Covers final expenses, smaller death benefit.

Choosing the right type of life insurance policy depends on your personal financial situation, goals, and the needs of your family. It's important to weigh the benefits and limitations of each option to determine which aligns best with your long-term objectives.

Evaluating the Role of Life Insurance in Financial Planning

Life insurance serves as a cornerstone in the architecture of a comprehensive financial plan. It ensures that your family's financial needs will be met, even in your absence. This protection extends beyond mere peace of mind; it is a strategic move to safeguard your family's future.

Life insurance is not just about leaving a legacy, but about planning for the unexpected and ensuring that your loved ones can maintain their lifestyle without financial burden.

When considering life insurance in your financial planning, it's important to evaluate several factors:

  • The potential loss of income and how it would affect your family

  • Outstanding debts and mortgages that need to be covered

  • Future educational costs for children

  • Long-term goals such as retirement savings for your spouse

By addressing these areas, you can determine the level of coverage necessary to provide adequate protection. Remember, life insurance is not a static product; it should evolve with your life stages and financial goals.

Assessing Your Life Insurance Needs

Assessing Your Life Insurance Needs

Analyzing Financial Obligations and Future Goals

When considering life insurance, it's crucial to analyze your financial obligations and future goals. This step is not just about numbers; it's about understanding the impact of your absence on those who depend on you.

  • Financial Responsibilities: Assess your current debts, such as mortgages, loans, and living expenses. These are the immediate needs that your life insurance must cover.

  • Income Replacement: Estimate the income required to sustain your family's lifestyle. This includes your salary, potential future earnings, and any other financial resources.

  • Future Goals: Consider long-term objectives like education for children, retirement savings, and any significant future expenses.

It's a testament to foresight to prepare for these eventualities, ensuring that your family's future is secure and their aspirations are achievable.

Remember, the right life insurance plan is one that aligns with your unique financial landscape and supports your family's journey through life's milestones.

Determining Coverage Amounts

Determining the right amount of life insurance coverage is a critical step in securing your family's financial future. The rule of thumb is to have a policy worth 10-12 times your annual income, but this is just a starting point. Each family's situation is unique, and the coverage should reflect that.

When evaluating how much coverage you need, consider the following:

  • Current and future financial obligations

  • Income replacement for dependents

  • Debts and mortgages

  • Education costs for children

  • End-of-life expenses

It's essential to not only look at your current financial situation but also to project future needs and potential changes in circumstances.

Remember to review the policy details carefully, including the coverage limits and any exceptions that may apply. This ensures that the policy provides adequate protection without leaving any gaps. Additionally, inquire about potential discounts or lower rates that could make the insurance more affordable without compromising on the coverage.

Considering Life Stages and Family Dynamics

Life insurance needs are not static; they evolve as you move through different life stages and as your family dynamics change. Choosing the right life insurance policy involves considering these personal milestones and how they affect your financial responsibilities.

  • The Student Stage: Securing your future can start early, with policies that cover education loans and provide peace of mind to parents.

  • Parenthood: This stage brings the joy of adding a new member to your family, along with the need to plan for their upbringing, education, and health.

  • Major Life Events: Marriage, divorce, and the birth of a child are just a few events that should prompt a review of your life insurance coverage.

It's essential to adapt your life insurance as your life unfolds. Regularly updating your policy to reflect significant life changes ensures that your coverage aligns with your current needs and goals.

Comparing Life Insurance Policies

Comparing Life Insurance Policies

Term Life Versus Permanent Life Insurance

When deciding between term and permanent life insurance, understanding the key differences is crucial. Term life insurance is designed to provide coverage for a specific period, such as 10, 20, or 30 years, and is often chosen for its lower premiums. It's a suitable option for those looking to protect their family's financial needs during critical periods, like when raising children or paying off a mortgage.

On the other hand, permanent life insurance offers lifelong coverage and includes a cash value component that grows over time. This type of policy is more complex and typically comes with higher premiums but can serve as both a death benefit and a savings or investment vehicle.

Here's a quick comparison:

  • Term Life Insurance: Temporary coverage, no cash value, fixed premiums, coverage ends after the term.

  • Permanent Life Insurance: Lifetime coverage, potential cash value accumulation, higher premiums.

Choosing the right type of life insurance policy depends on your individual needs, financial goals, and the level of coverage you desire. It's important to weigh the benefits and limitations of each before making a decision.

Understanding Policy Features and Benefits

When comparing life insurance policies, it's crucial to look beyond the surface to understand the policy features and benefits that can provide additional security. These features, often referred to as riders, can significantly enhance the value of a policy. For instance, an accelerated death benefit allows for early payout under certain conditions, while a waiver of premium ensures your coverage continues even if you become disabled and unable to pay premiums.

  • Policy Features and Riders:

    • Accelerated death benefits

    • Waiver of premium

    • Guaranteed insurability options

It's essential to know the details of how life insurance works, as the right features can transform a policy from a simple contract into a dynamic part of your financial safety net.

Understanding the implications of policy stipulations is just as important as the benefits. Questions should be asked to clarify how the policy functions in various scenarios, such as filing a claim or adjusting to life changes. Additionally, be aware of policy exceptions and exclusions, as they can critically impact the effectiveness of your coverage.

How to Read and Compare Policy Quotes

When venturing into the realm of life insurance, understanding how to effectively read and compare policy quotes is crucial. Begin by gathering quotes from several insurers, ensuring that each quote is based on the same policy type, coverage amount, and personal information. This standardization allows for an apples-to-apples comparison, giving you a clearer picture of the value each policy offers.

It's essential to delve beyond the surface numbers and scrutinize the finer details of each policy. Consider the implications of policy stipulations on your daily life and future financial planning. Ask pointed questions to gain a transparent understanding of how the policy functions in the event of a claim and how it aligns with your changing needs.

To aid in this comparison, a structured approach can be helpful. Here's a simple checklist to keep in mind:

  • Confirm that the coverage amounts are identical.

  • Check the term length for term insurance policies.

  • Evaluate the premium costs, but also the benefits and exclusions.

  • Review the financial stability and ratings of the insurance providers.

  • Consider the customer service reputation and claims process of each company.

Choosing the Right Life Insurance Provider

Choosing the Right Life Insurance Provider

Researching Insurance Companies

When selecting a life insurance provider, it's crucial to conduct thorough research to ensure that your family's future is in reliable hands. Start by investigating the insurer's financial stability; this is a non-negotiable aspect as it reflects the company's ability to honor claims over time. Established agencies such as A.M. Best or Standard & Poor's provide credit ratings and financial statements that are indispensable in this evaluation.

Next, delve into customer satisfaction ratings and seek out testimonials and third-party reviews. These insights offer a glimpse into the insurer's track record with clients and can highlight the experiences of other policyholders. It's important to partner with a company that not only fits your coverage needs but also upholds a reputation of integrity and responsiveness.

Remember, the choice of an insurance company is as significant as the policy itself. The right provider should be a pillar of trust, demonstrating a consistent track record of reliability and fiscal responsibility.

Lastly, consider the resources available for ongoing education and analysis of insurance issues. Organizations like the Center for Insurance Policy and Research - NAIC play a pivotal role in driving dialogue and action on current insurance matters.

Evaluating Customer Service and Claims Process

When selecting a life insurance provider, assessing the quality of customer service and the claims process is crucial. This involves considering how accessible and responsive the insurer is, as well as the efficiency and transparency of their claims processing. Customer reviews and testimonials can provide valuable insights into the satisfaction of current policyholders.

Understanding the claims process is essential. Familiarize yourself with the necessary steps, required documents, and expected response times to prevent delays during stressful times.

It's important to treat each review and testimonial as a significant indicator of the insurer's reliability. Real-life experiences can reveal how the company performs when it matters most. Additionally, examining customer satisfaction ratings can give you a clear view of the insurer's service quality and claims handling.

Checking Financial Stability and Ratings

When selecting a life insurance provider, checking their financial stability and ratings is crucial. These ratings are a reflection of the insurer's ability to meet its financial obligations and are indicative of its overall health and longevity. Agencies such as A.M. Best or Standard & Poor's provide these ratings based on a comprehensive analysis of the insurer's financial strength, performance, and market position.

It's essential to review an insurer's long-term financial statements and credit ratings to gauge their resilience against market fluctuations and their capability to honor claims.

For a quick reference, here's a simplified table showing how ratings can be interpreted:

Rating Agency

Rating

Interpretation

A.M. Best

A++

Superior

A.M. Best

A

Excellent

JD Power

881

High Satisfaction

Remember, a high customer satisfaction rating often correlates with a company's efficiency in handling claims and addressing client concerns.

Maintaining and Reviewing Your Life Insurance

Maintaining and Reviewing Your Life Insurance

Updating Your Policy to Reflect Life Changes

Life insurance is a dynamic commitment that should evolve as your life does. Significant life events such as marriage, the birth of a child, or a change in financial status necessitate a policy review and update. It's crucial to ensure that your coverage amounts and beneficiary designations are in sync with your current circumstances.

  • Review beneficiary designations to reflect current relationships.

  • Adjust coverage amounts to align with new financial responsibilities.

  • Consider the impact of career changes on your insurance needs.

Regularly monitoring the performance of your policy, including any cash value growth or investment returns, is essential to maintain its effectiveness over time. This vigilance helps in keeping the policy aligned with both evolving needs and budgetary constraints.

Remember, life insurance is not a static purchase; it's a protection plan that should be revisited periodically. Whether it's due to personal milestones or changes in your financial landscape, updating your policy is a proactive step towards ensuring your family's security.

The Importance of Regular Policy Reviews

Life insurance is a dynamic commitment that requires ongoing attention to ensure it remains in sync with your life's evolution. Regular policy reviews are crucial to maintaining a safety net that adapts to your changing circumstances. These reviews allow you to adjust coverage, premiums, and benefits to fit new life milestones such as marriage, the birth of a child, or purchasing a home.

  • Review your policy in the context of major life events.

  • Assess the balance between premium costs and the coverage benefits.

  • Scrutinize policy exceptions to avoid uncovered risks.

Vigilance in policy review is not just about keeping premiums in check; it's about ensuring that your coverage continues to align with your family's needs and your financial goals.

By engaging with your insurance provider and reevaluating your policy periodically, you can protect your family's future and create a lasting legacy. It's not just about the possibility of large debts or financial support after death; it's about the peace of mind that comes from knowing your loved ones are protected.

When to Consider Increasing or Decreasing Coverage

Life insurance is not a static entity; it should evolve with your life's journey. Regular reviews of your policy are crucial to ensure that your coverage aligns with your current needs and life circumstances. Significant life events such as marriage, the birth of a child, or the purchase of a home may necessitate an increase in coverage to provide adequate protection for your growing responsibilities.

Conversely, there may be times when decreasing your coverage is appropriate. As children grow up and become independent, or a mortgage is paid off, your financial obligations may diminish. This could be an opportunity to lower your premiums while still maintaining a safety net.

It's essential to strike a balance between being over-insured, which can unnecessarily strain your finances, and being under-insured, which can leave your family vulnerable. Evaluating your coverage periodically allows you to make informed decisions about adjusting your policy.

Remember to consider the potential impact of reducing coverage. By reassessing your coverage needs, you can ensure that your policy continues to meet your financial goals without leaving gaps in protection or paying for unnecessary coverage.

Conclusion

In conclusion, securing the right life insurance policy is a pivotal decision that safeguards your family's financial future. Throughout this guide, we've explored the importance of aligning a policy with your personal goals, understanding the various types of insurance available, and the significance of thorough research. Remember, life insurance is not a one-size-fits-all solution; it requires careful consideration of your unique circumstances and needs. By following the steps outlined, you can confidently navigate the market to find a policy that offers peace of mind and stability for your loved ones. Keep in mind that life is ever-changing, and so should your coverage. Regularly reviewing and adjusting your life insurance ensures that it remains in step with your life's journey. Invest the time now to make an informed choice, and you'll provide a lasting legacy of security for those you cherish most.

Frequently Asked Questions

What are the main types of life insurance policies available?

The main types of life insurance policies include term life insurance, which provides coverage for a specific period, and permanent life insurance, such as whole life and universal life, which offer lifelong coverage and may include a cash value component.

How do I determine the right amount of life insurance coverage for my family?

To determine the right coverage amount, consider your financial obligations, future goals, income replacement needs, and any debts or expenses your family would need to cover in the event of your passing. A financial advisor can help you calculate a suitable amount.

What factors should I consider when choosing a life insurance provider?

When choosing a provider, research the company's reputation, financial stability, customer service record, and claims process. Look for ratings from independent agencies and read reviews from current policyholders.

How often should I review my life insurance policy?

It's recommended to review your life insurance policy at least every few years or after major life events such as marriage, divorce, the birth of a child, or a significant change in financial circumstances to ensure your coverage remains adequate.

Can I change my life insurance policy if my needs change?

Yes, many life insurance policies allow for adjustments. You may be able to increase or decrease coverage, change beneficiaries, or even convert a term policy to a permanent one, depending on the terms of your policy.

Is life insurance necessary at every stage of life?

Life insurance needs can vary depending on your life stage and financial responsibilities. While it's commonly sought after by those with dependents or significant debts, even individuals without dependents may benefit from life insurance to cover end-of-life expenses or leave a legacy.

Understanding Cash Value in Life Insurance Policies

 Life insurance is a crucial component of financial planning, offering not only protection for loved ones in the event of one's passing but also, in some cases, a savings component known as cash value. Understanding cash value in life insurance policies is essential for policyholders who want to maximize their financial strategy. This article demystifies the concept of cash value, examining its accumulation, benefits, risks, and the various ways it can be accessed and utilized within permanent life insurance policies.

Key Takeaways

  • Cash value is a unique feature of permanent life insurance policies, serving as a savings component that grows tax-deferred over time.

  • Premium payments in cash value policies are allocated to both the insurance cost and the savings component, enabling the cash value to accumulate.

  • Policyholders can access their cash value through withdrawals, loans, or policy surrender, each with distinct tax implications and financial consequences.

  • While cash value can offer financial flexibility and growth, it also comes with potential risks and costs that must be carefully evaluated.

  • Consulting with financial experts and comparing different cash value life insurance products can help individuals make informed decisions that align with their financial goals.

The Basics of Cash Value in Life Insurance

The Basics of Cash Value in Life Insurance

Defining Cash Value and Its Role in Permanent Policies

Cash value is a distinctive feature of permanent life insurance policies, serving as a financial reservoir that policyholders can tap into under certain conditions. It represents the savings component of a policy that accumulates value over time. This cash value grows tax-deferred, meaning taxes on the interest or investment gains are not paid until the money is withdrawn.

The role of cash value in permanent policies is multifaceted:

  • It can be used to pay premiums, effectively lowering the out-of-pocket cost for the insurance.

  • Policyholders may borrow against the cash value for loans, which can be used for various personal expenses.

  • In some cases, it can serve as an additional source of retirement income or fund long-term care needs.

While cash value adds a layer of financial utility to life insurance, it's important to weigh the benefits against the costs and potential impact on the death benefit.

Understanding the implications of cash value is crucial for policyholders, as it affects both the present financial flexibility and future benefits of the life insurance policy.

Types of Life Insurance Policies with Cash Value Features

Life insurance policies with cash value features are distinct from term life insurance, which lacks this component. Whole life, universal life, and variable life insurance are the primary types of permanent policies that include a cash value feature. Each type offers unique approaches to premium payments and cash value growth.

  • Whole life insurance guarantees a fixed premium and a cash value that grows at a predetermined rate.

  • Universal life insurance provides more flexibility with premium payments and cash value growth based on market interest rates.

  • Variable life insurance allows policyholders to invest the cash value in various investment options, which can lead to higher growth potential but also comes with increased risk.

Cash value is a crucial aspect of permanent life insurance, enabling policyholders to accumulate a tax-deferred balance that can be accessed during their lifetime. It's important to understand that in the early years, cash value growth is typically slow, but it accelerates over time, potentially offering a higher return.

Comparing Cash Value to the Death Benefit

Understanding the distinction between cash value and the death benefit is crucial in evaluating life insurance policies. The death benefit is the amount paid to beneficiaries upon the policyholder's death, while the cash value serves as a savings component that can be accessed during the policyholder's lifetime.

The cash value is not intended for beneficiaries and typically reverts back to the insurance company upon the policyholder's death. However, certain policies may offer both the death benefit and cash value, but at a higher cost.

Cash value can be utilized in various ways, such as reducing premium payments, supplementing retirement income, or covering unexpected expenses. It's important to note that the method of cash value payout can differ based on the type of policy. For instance, universal life policies may allow the cash value to be paid out as part of, or in addition to, the death benefit.

Mechanics of Cash Value Accumulation

Mechanics of Cash Value Accumulation

How Premium Payments Contribute to Cash Value

When you purchase a cash value life insurance policy, your premium payments are allocated in several ways. A portion of each premium contributes directly to the cash value, which grows over time. This growth is tax-deferred, meaning you won't pay taxes on the gains as they accrue.

The allocation of premium payments can be broken down as follows:

  • Policy fees and charges

  • The cost of the insurance coverage

  • The cash value account

Depending on the type of policy, the cash value may earn a fixed interest rate or vary with market performance. It's essential to recognize that not all of your premium goes into the cash value; a significant part covers the insurance and associated fees.

Accessing the cash value can be done through withdrawals or loans, but these actions may affect the policy's benefits and the death benefit amount. It's crucial to understand the terms and potential consequences before utilizing the cash value.

The Impact of Interest and Investment on Cash Value Growth

The growth of cash value in a life insurance policy is significantly influenced by the interest rate or investment performance. Policies with a fixed interest rate provide a steady, predictable increase in cash value over time. In contrast, policies tied to investment performance can see more variable growth, often reflecting market conditions.

  • Your policy's interest rate or investment choices determine the rate of cash value accumulation.

  • Market-linked policies may have a minimum guaranteed return (floor) and a maximum growth cap (ceiling).

  • Comparatively, direct investments in stocks or mutual funds may offer higher returns but come with increased risk.

The balance between stability and potential for growth is a key consideration when evaluating the suitability of cash value life insurance as an investment.

It's important to understand that while some policies guarantee a minimum rate of return, others allow for participation in potentially higher gains from market performance, albeit with a ceiling to limit maximum growth. This structure aims to provide a level of protection against market volatility while offering the opportunity for cash value appreciation.

Understanding Policy Loans and Withdrawals

Policyholders have the flexibility to access their policy's cash value through loans and withdrawals, each with its own set of implications. Withdrawals reduce the death benefit by the amount taken out, as they are a direct removal of funds from the policy's cash value. This can be advantageous for immediate financial needs or significant life events, like purchasing a home.

Loans, on the other hand, allow policyholders to borrow against their cash value. These loans typically do not require a credit check and may offer lower interest rates compared to traditional loans. While not mandatory, repaying the loan is beneficial to maintain the policy's full death benefit. Failure to repay can result in a reduced death benefit, as the outstanding loan amount plus interest will be deducted.

The strategic use of policy loans and withdrawals can enhance the utility of a life insurance policy, making it a dynamic financial instrument.

It's crucial to understand the tax implications of these actions. Withdrawals are generally tax-free up to the amount of premiums paid, but loans are not considered taxable income. However, if the policy lapses with an outstanding loan, the amount exceeding the premiums paid may be taxed as income.

Advantages and Drawbacks of Cash Value Policies

Advantages and Drawbacks of Cash Value Policies

The Financial Benefits of Building Cash Value

Building cash value within a life insurance policy offers a unique blend of financial security and wealth accumulation. The cash value acts as a savings component, growing over time and providing a range of benefits that extend beyond the traditional death benefit. Here are some of the key financial advantages:

  • Tax-deferred growth: The cash value in your policy grows without immediate tax implications, allowing your investment to compound more efficiently over time.

  • Loan collateral: You can borrow against the cash value of your policy, often at favorable interest rates, without disrupting the policy's death benefit.

  • Flexible use of funds: Access to cash value can provide financial support for various needs, such as supplementing retirement income or covering unexpected expenses.

The strategic use of cash value can significantly enhance your financial planning, offering a versatile tool for managing both present and future financial challenges.

It's important to note that while the benefits are substantial, they must be balanced against the costs and risks associated with cash value policies. Careful consideration and planning are essential to ensure that a cash value life insurance policy aligns with your long-term financial objectives.

Potential Risks and Costs Associated with Cash Value

While cash value life insurance offers a savings component and the potential for growth, it's important to be aware of the risks and costs involved. Policies with cash value are generally more expensive than term life insurance, as a portion of your premium goes towards building the cash value.

  • More expensive premiums: The cost of premiums is higher compared to term life insurance.

  • Interest and tax complications: Loans against the cash value may incur interest and create potential tax liabilities.

  • Reduced death benefit: Taking out loans against the policy can reduce the death benefit available to beneficiaries.

  • Growth takes time: Building a significant cash value can take many years, and early withdrawals may have financial penalties.

It's crucial to consider these factors in the context of your overall financial plan and to consult with a financial advisor to determine if a cash value policy aligns with your goals.

Evaluating the Suitability of Cash Value Life Insurance for Your Financial Goals

When considering cash value life insurance, it's essential to assess how well it aligns with your financial objectives. This type of policy combines a death benefit with a savings component, allowing the cash value to grow over time. Here are some factors to consider:

  • Long-term financial goals: Is building a tax-deferred savings account for retirement or future expenses important to you?

  • Financial flexibility: Do you value the option to borrow against the policy or make withdrawals during your lifetime?

  • Costs versus benefits: Are the potential growth and the financial benefits worth the typically higher premiums compared to term life insurance?

It's crucial to understand that cash value life insurance is not merely an expense but an investment in your future financial security. However, it's not suitable for everyone, and the decision should be based on a thorough analysis of your individual circumstances.

Before making a decision, consider speaking with a financial advisor to determine if a cash value policy makes sense for you. They can help you weigh the pros and cons, taking into account your unique financial situation and goals.

Accessing Your Policy's Cash Value

Accessing Your Policy's Cash Value

Options for Withdrawing Cash Value

Policyholders have several avenues to access the cash value of their life insurance policies. Withdrawing funds directly is a straightforward method, allowing you to use the cash for any purpose, from emergency expenses to planned investments like a home down payment. However, it's crucial to remember that such withdrawals can reduce the remaining death benefit.

Another common option is to take out a loan against the cash value. This approach provides liquidity without an immediate reduction in the death benefit, but it does come with the obligation to repay the loan with interest. Failure to repay can lead to a decrease in the death benefit or policy lapse.

Policyholders may also use their accumulated cash value to cover premium payments, which can help maintain the policy without out-of-pocket expenses.

Lastly, full or partial surrender of the policy is possible, though this often comes with tax implications, especially if the withdrawal amount exceeds the premiums paid.

The Tax Implications of Accessing Cash Value

When you access the cash value of your life insurance policy, the tax implications can vary based on the method and amount you withdraw. Withdrawals up to the amount of premiums paid are generally not taxable. However, amounts exceeding the premiums paid are subject to income tax.

  • Scenario 3: Withdrawing partially or fully may result in taxes on the excess over premiums paid.

  • Scenario 4: Using cash value to pay premiums is typically not taxable.

The cash value in a life insurance policy grows tax-deferred, meaning you won't owe taxes on the growth until you withdraw the funds. It's crucial to understand that policy loans and withdrawals reduce the death benefit and may take a considerable time to build up, potentially affecting the long-term value of your policy.

Strategies for Maximizing Your Policy's Cash Value Potential

To enhance the growth of your policy's cash value, consider these strategies:

  • Regularly review your policy's performance to ensure it aligns with your financial goals. Adjust your investment choices in variable policies to respond to market conditions and optimize returns.

  • Reinvest dividends back into your policy to increase the cash value.

  • Use the cash value to pay premiums, which can help sustain the policy and continue its growth without out-of-pocket expenses.

By strategically managing your policy, you can leverage the cash value as a tool for wealth building and financial planning.

Remember, the cash value of your policy can serve multiple purposes. It can be used to supplement retirement income, cover long-term care costs, or even reduce your premium payments. The key is to balance the use of cash value with the preservation of the death benefit for your beneficiaries.

Making an Informed Decision on Cash Value Life Insurance

How to Assess Different Cash Value Life Insurance Products

When evaluating cash value life insurance products, it's crucial to understand the nuances that differentiate one policy from another. Consider the policy's flexibility, such as the ability to adjust premium payments and the ease of accessing cash value. Assess the investment component, which can significantly influence the growth of the cash value over time.

  • Review the types of policies available: whole life, universal life, and variable life insurance.

  • Compare the interest rates or investment returns each policy offers.

  • Examine the fee structure, including premiums, administrative fees, and potential penalties for early withdrawal.

It's essential to align the policy's features with your long-term financial objectives, ensuring it complements your overall financial plan.

Finally, scrutinize the insurer's financial strength and reputation, as this will impact the security of your investment. Policies should be compared not just on their projected cash value growth, but also on the company's track record of reliability and customer service.

Consulting with Financial Experts on Cash Value Benefits

When considering cash value life insurance, consulting with financial experts can provide clarity and confidence in your decision. Experts can tailor advice to your unique financial situation, ensuring that the policy aligns with your long-term goals and investment strategy. They can help you understand complex policy details, such as fees, surrender charges, and the implications of loans and withdrawals on your policy's value.

  • Evaluate your financial goals and needs

  • Analyze the long-term performance of different cash value policies

  • Consider tax implications and potential risks

  • Develop a strategy for integrating the policy with your overall financial plan

Financial experts can offer insights into how cash value life insurance fits into a diversified portfolio and its role in estate planning. Their guidance is invaluable in navigating the nuances of these policies and in making an informed decision that benefits your financial future.

Real-life Examples and Case Studies of Cash Value Utilization

Understanding how cash value in life insurance works in real-life scenarios can provide valuable insights into its practical benefits and applications. Case studies often reveal the versatility of cash value, demonstrating how individuals can use it to address various financial needs throughout their lifetimes.

  • John Doe, at age 45, borrowed against his policy's cash value to fund his child's college education, avoiding the need for student loans.

  • Jane Smith, a retiree, supplemented her income by making systematic withdrawals from her policy's cash value, thus maintaining her lifestyle without depleting other retirement savings.

  • The Johnson Family Trust utilized the cash value of their policy to settle estate taxes, ensuring a smooth transfer of assets to beneficiaries.

The strategic use of cash value can significantly impact financial planning, offering a flexible tool for managing life's unpredictable expenses.

It's important to note that while accessing cash value can be advantageous, it must be done with a clear understanding of the policy's terms and the potential impact on the death benefit. Professional advice is recommended to navigate these decisions effectively.

Conclusion

In summary, cash value life insurance policies offer a unique combination of death benefit protection and a savings component that accumulates value over time. While these policies can serve as a financial tool for long-term planning, they may not be suitable for everyone. Understanding the intricacies of how cash value accumulates, the types of policies available, and the potential disadvantages is crucial for making an informed decision. If you're considering a cash value life insurance policy, it's important to weigh the benefits against the costs and to consult with a financial advisor to ensure it aligns with your overall financial strategy. For those seeking guidance, our life insurance specialists are available to help you navigate your options and make the choice that best suits your needs.

Frequently Asked Questions

What is cash value in a life insurance policy?

Cash value in a life insurance policy refers to a savings component that is part of permanent life insurance policies. A portion of each premium payment is allocated to this cash value account, where it can earn interest or be invested, growing tax-deferred over time.

How does cash value accumulate in a life insurance policy?

Cash value accumulates in a life insurance policy when a portion of the premium payments is invested by the insurance company into various assets. This can include stocks, bonds, or mutual funds, and the value of these investments grows over time, adding to the policy's cash value.

Can I access the cash value in my life insurance policy?

Yes, policyholders can access the cash value in their life insurance policy through withdrawals, policy loans, or by surrendering the policy. However, accessing the cash value can have tax implications and may reduce the death benefit.

What types of life insurance policies include a cash value feature?

Permanent life insurance policies, such as whole life and universal life insurance, include a cash value feature. This is in contrast to term life insurance, which does not have a cash value component.

Are there any disadvantages to cash value life insurance?

Cash value life insurance policies typically have higher premiums than term life insurance, and accessing the cash value can reduce the death benefit. Additionally, there are fees and potential tax consequences associated with cash value withdrawals or loans.

How do I know if cash value life insurance is right for me?

Determining if cash value life insurance is right for you depends on your financial goals, need for permanent coverage, and desire for a savings component. It's important to consult with a financial advisor to assess your individual situation and consider all potential risks and benefits.