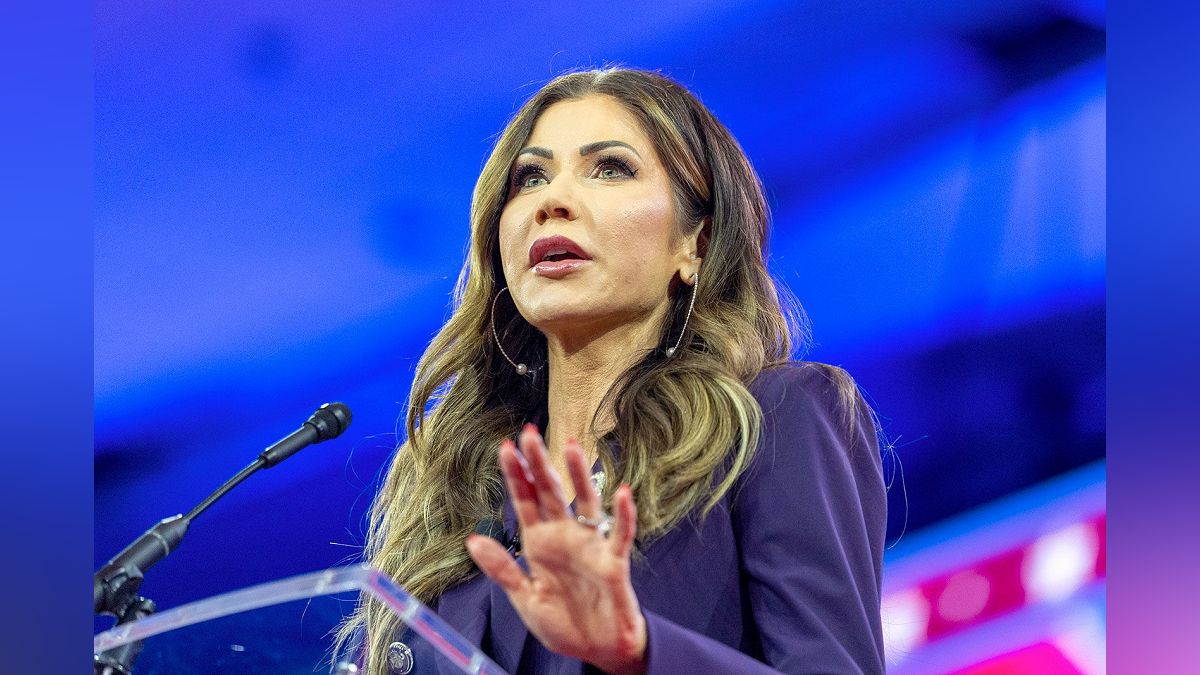
South Dakota Governor Kristi Noem has been a prominent figure in American politics, known for her staunch conservative stance and alignment with Christian nationalist ideologies. Her tenure as governor has been marked by several bold policies that have sparked both admiration and controversy. From her unwavering support for anti-abortion legislation to her endorsement of former President Donald Trump, Noem's actions have consistently made headlines. This article explores five key policies that have come to define her time in office, shedding light on the values and strategies that underpin her governance.
Key Takeaways
Governor Noem's special legislative session on abortion aimed to further restrict abortion access, showcasing her commitment to the anti-abortion movement.
Her steadfast support for former President Donald Trump has solidified her position within the conservative base and raised her profile as a potential vice-presidential candidate.
Noem's advocacy for Christian nationalist ideologies emphasizes the role of Christianity in American public life, aligning with a movement that seeks to shape government and society according to Christian values.
The Smile Texas endorsement controversy raised ethical questions about the use of personal social media for potential political gain and blurred lines between personal endorsements and official duties.
Sponsorship of the Cinch Playoffs Governor's Cup using taxpayer money has been criticized for the use of public funds in support of private events, reflecting Noem's willingness to merge governance with personal interests.
1. Right to Life Special Legislative Session
Governor Kristi Noem has been a staunch advocate for anti-abortion policies, calling a special legislative session to address 'Right to Life' issues. This session underscored her commitment to enacting laws that would significantly restrict abortion access in her state.
During the session, several measures were considered, reflecting a broader national trend where states have proposed stringent abortion laws. For instance, some states have introduced bills that would classify abortion as homicide, while others have pursued near-total bans on the procedure, with exceptions only to save the life of the pregnant woman.
The legislative efforts in South Dakota and across the country have sparked intense debate and have become a central aspect of Noem's tenure, highlighting the polarized views on abortion rights.
While Noem's actions align with her conservative base, they have also attracted criticism and legal challenges, emphasizing the contentious nature of abortion legislation in the current political climate.
2. Support for Former President Donald Trump
Throughout her tenure, Governor Kristi Noem has been a staunch supporter of former President Donald Trump. Her endorsement played a pivotal role in the political landscape, particularly as Trump sought to solidify his base for a potential 2024 presidential bid.
Governor Noem's alignment with Trump's policies and her public backing have underscored her commitment to the former president's agenda.
Several key endorsements from influential figures have emerged in support of Trump, reflecting a broader trend among Republican leaders:
Rep. Mike Johnson, despite previous reservations, declared he is "all in" for Trump's 2024 run.
Florida Congressman Carlos Gimenez and West Virginia AG Patrick Morrisey have also thrown their support behind Trump.
Notably, Arkansas Gov. Sanders and Rep. Burgess Owens have publicly endorsed Trump, signaling strong GOP backing.
These endorsements come amidst legal challenges and political controversies surrounding the former president, yet they demonstrate the unwavering loyalty of his allies within the party.
3. Christian Nationalist Advocacy
Governor Kristi Noem's political career has been marked by a strong advocacy for the integration of Christian principles into American governance, a stance that aligns with Christian nationalist ideologies. Her public statements and policies often reflect a commitment to traditional Christian values, which has garnered support from like-minded constituents.
During her tenure, Noem has found traction among groups that seek to influence government and education with Christian values. These groups advocate for a greater role of Christianity in public life, often through various means:
Church United: Aiming to mobilize churches politically, criticized for promoting a Christian nationalist agenda.
Church Voter Lookup: A tool for identifying and mobilizing Christian voters to support 'Christian values' candidates.
Christian Satellite Network: While not overtly nationalist, it broadcasts content that resonates with nationalist views.
J. C. Church: A pastor and political activist promoting the integration of Christian principles into governance.
The intersection of faith and politics under Noem's leadership has been a defining feature of her administration, sparking both support and controversy.
4. Smile Texas Endorsement Controversy
The Smile Texas Endorsement Controversy highlights a significant moment in Kristi Noem's tenure, where the intersection of politics and education sparked legal and ethical debates. Allegations arose that state resources were improperly used to influence electoral outcomes, a clear violation of the Texas Election Code. This controversy underscores the delicate balance between political advocacy and the legal boundaries set for public officials and institutions.
The essence of the controversy lies in the misuse of state resources for political endorsements, a practice that undermines the integrity of democratic processes and the trust in public education systems.
The implications of such actions are far-reaching, with potential consequences for the integrity of elections and the role of public institutions in political discourse. The controversy serves as a reminder of the importance of adhering to legal standards and the scrutiny public figures face in their endorsements.
5. Cinch Playoffs Governor's Cup Sponsorship
In a move that showcased her support for traditional sports and local culture, Governor Kristi Noem made headlines when she rode into a Sioux Falls arena, flag in hand, during the Cinch Playoffs Governor's Cup. This event, which boasted a prize pool of $1 million, was not just a spectacle of rodeo talent but also a beneficiary of public funds, a decision made by Noem herself.
The Governor's Cup sponsorship raised questions about the use of taxpayer dollars, as it was funded in part by South Dakota employers' tax contributions. While the event was a celebration of rodeo heritage, the financial backing from the state's Future Fund sparked a debate on the prioritization of public spending.
The involvement of public funds in such events is a delicate balance between promoting local culture and ensuring fiscal responsibility.
Despite the controversy, the Governor's Cup was a moment of pride for many, with Noem's participation adding to the event's allure. Her presence on social media, sharing images with her followers, underscored her connection with the community and her role in promoting South Dakota's traditions.
Conclusion
Governor Kristi Noem's tenure has been marked by a series of bold and controversial policies that have both defined her leadership and sparked national debate. From her unwavering stance on abortion to her alignment with Christian nationalist ideologies, Noem has consistently championed conservative values. Her actions, such as the special session to address abortion laws and the endorsement of Trump's energy policies, underscore her commitment to her political base. However, her governance has also raised questions, particularly concerning the use of taxpayer dollars and her position on businesses aiding in abortion access. As Noem navigates the complexities of political ethics and potential presidential aspirations, her policy decisions continue to shape South Dakota's legislative landscape and her own political trajectory.
Frequently Asked Questions
What is the significance of the Right to Life Special Legislative Session called by Kristi Noem?
Governor Kristi Noem called a special legislative session to address abortion laws, aiming to 'guarantee that every unborn child has a right to life in South Dakota' following the U.S. Supreme Court's decision to overturn Roe v. Wade.
How has Kristi Noem shown her support for former President Donald Trump?
Kristi Noem has been an outspoken supporter of Donald Trump, endorsing his policies and aligning with his political agenda, including advocating for America to have the lowest cost energy and electricity.
What role does Christian Nationalism play in Kristi Noem's governance?
Kristi Noem's governance is characterized by her advocacy for Christian nationalist ideologies, emphasizing the role of Christianity in American public life and reflecting traditional Christian values.
What controversy arose from Kristi Noem's endorsement at the Cinch Playoffs Governor's Cup?
The controversy stemmed from Governor Noem's use of tax dollars to sponsor the Cinch Playoffs Governor's Cup, an event that she participated in, which raised questions about the appropriate use of public funds.
What is the Smile Texas Endorsement Controversy involving Kristi Noem?
Kristi Noem faced scrutiny for promoting Smile Texas, a cosmetic dentistry clinic, after receiving dental work there. The endorsement raised ethical questions due to her position as governor.
What is the significance of the Cinch Playoffs Governor's Cup sponsorship by Kristi Noem?
The sponsorship of the Cinch Playoffs Governor's Cup by Governor Noem signified her support for the event, but it also sparked debate about the use of state funds for promotional activities.
Life insurance is a crucial component of financial planning, providing peace of mind and financial security for you and your loved ones. With numerous options available in the market, finding the best life insurance policy can seem overwhelming. However, by understanding your needs, exploring different types of policies, and comparing providers, you can make an informed decision that aligns with your goals. In this comprehensive guide, we'll delve into the key factors to consider when choosing the best life insurance policy to protect your future and your family's financial well-being.
Key Takeaways
Understanding life insurance basics is essential for making an informed decision about the best policy for your family's needs.
Assessing your financial obligations and future goals is crucial to determining the right coverage amount for your life insurance.
Comparing life insurance policies involves looking at the differences between term and permanent life insurance and evaluating policy features and benefits.
Choosing the right life insurance provider requires research into the company's customer service, claims process, and financial stability.
Maintaining and reviewing your life insurance policy is important to ensure it continues to meet your changing needs and provides adequate coverage.
Understanding Life Insurance Basics
Defining Life Insurance and Its Importance
Life insurance is a fundamental agreement between an individual and an insurance company. Essentially, you pay regular premiums so that in the event of your death, the insurer will provide a death benefit to your designated beneficiaries. This benefit is a crucial financial safety net, ensuring that your loved ones are not left with a financial burden.
Who should consider life insurance? It's particularly important for those who are the primary earners in their families, parents, homeowners, or individuals with significant debts that could be transferred to others. Beneficiaries have the flexibility to use the death benefit for various needs, such as settling debts, replacing lost income, or managing funeral expenses.
Primary earners: To replace lost income
Parents: To secure children's future
Homeowners: To cover mortgage obligations
Debt holders: To settle co-signed debts
Life insurance is not just a purchase but an investment in the peace of mind for you and your family. It's a promise that they will be taken care of, even in your absence.
Types of Life Insurance Policies
When considering life insurance, understanding the different types of policies available is crucial. Term life insurance offers temporary coverage for a set period, such as 10, 20, or 30 years, with fixed premiums and a death benefit but no cash value. On the other hand, permanent life insurance, including whole life and universal life, provides lifetime coverage with the potential for cash value accumulation.
Term Life Insurance: Temporary coverage, fixed premiums, no cash value.
Whole Life Insurance: Permanent coverage, potential cash value.
Universal Life Insurance: Flexible premiums, adjustable benefits.
Variable Life Insurance: Investment options, variable cash value.
Burial Insurance: Covers final expenses, smaller death benefit.
Choosing the right type of life insurance policy depends on your personal financial situation, goals, and the needs of your family. It's important to weigh the benefits and limitations of each option to determine which aligns best with your long-term objectives.
Evaluating the Role of Life Insurance in Financial Planning
Life insurance serves as a cornerstone in the architecture of a comprehensive financial plan. It ensures that your family's financial needs will be met, even in your absence. This protection extends beyond mere peace of mind; it is a strategic move to safeguard your family's future.
Life insurance is not just about leaving a legacy, but about planning for the unexpected and ensuring that your loved ones can maintain their lifestyle without financial burden.
When considering life insurance in your financial planning, it's important to evaluate several factors:
The potential loss of income and how it would affect your family
Outstanding debts and mortgages that need to be covered
Future educational costs for children
Long-term goals such as retirement savings for your spouse
By addressing these areas, you can determine the level of coverage necessary to provide adequate protection. Remember, life insurance is not a static product; it should evolve with your life stages and financial goals.
Assessing Your Life Insurance Needs
Analyzing Financial Obligations and Future Goals
When considering life insurance, it's crucial to analyze your financial obligations and future goals. This step is not just about numbers; it's about understanding the impact of your absence on those who depend on you.
Financial Responsibilities: Assess your current debts, such as mortgages, loans, and living expenses. These are the immediate needs that your life insurance must cover.
Income Replacement: Estimate the income required to sustain your family's lifestyle. This includes your salary, potential future earnings, and any other financial resources.
Future Goals: Consider long-term objectives like education for children, retirement savings, and any significant future expenses.
It's a testament to foresight to prepare for these eventualities, ensuring that your family's future is secure and their aspirations are achievable.
Remember, the right life insurance plan is one that aligns with your unique financial landscape and supports your family's journey through life's milestones.
Determining Coverage Amounts
Determining the right amount of life insurance coverage is a critical step in securing your family's financial future. The rule of thumb is to have a policy worth 10-12 times your annual income, but this is just a starting point. Each family's situation is unique, and the coverage should reflect that.
When evaluating how much coverage you need, consider the following:
Current and future financial obligations
Income replacement for dependents
Debts and mortgages
Education costs for children
End-of-life expenses
It's essential to not only look at your current financial situation but also to project future needs and potential changes in circumstances.
Remember to review the policy details carefully, including the coverage limits and any exceptions that may apply. This ensures that the policy provides adequate protection without leaving any gaps. Additionally, inquire about potential discounts or lower rates that could make the insurance more affordable without compromising on the coverage.
Considering Life Stages and Family Dynamics
Life insurance needs are not static; they evolve as you move through different life stages and as your family dynamics change. Choosing the right life insurance policy involves considering these personal milestones and how they affect your financial responsibilities.
The Student Stage: Securing your future can start early, with policies that cover education loans and provide peace of mind to parents.
Parenthood: This stage brings the joy of adding a new member to your family, along with the need to plan for their upbringing, education, and health.
Major Life Events: Marriage, divorce, and the birth of a child are just a few events that should prompt a review of your life insurance coverage.
It's essential to adapt your life insurance as your life unfolds. Regularly updating your policy to reflect significant life changes ensures that your coverage aligns with your current needs and goals.
Comparing Life Insurance Policies
Term Life Versus Permanent Life Insurance
When deciding between term and permanent life insurance, understanding the key differences is crucial. Term life insurance is designed to provide coverage for a specific period, such as 10, 20, or 30 years, and is often chosen for its lower premiums. It's a suitable option for those looking to protect their family's financial needs during critical periods, like when raising children or paying off a mortgage.
On the other hand, permanent life insurance offers lifelong coverage and includes a cash value component that grows over time. This type of policy is more complex and typically comes with higher premiums but can serve as both a death benefit and a savings or investment vehicle.
Here's a quick comparison:
Term Life Insurance: Temporary coverage, no cash value, fixed premiums, coverage ends after the term.
Permanent Life Insurance: Lifetime coverage, potential cash value accumulation, higher premiums.
Choosing the right type of life insurance policy depends on your individual needs, financial goals, and the level of coverage you desire. It's important to weigh the benefits and limitations of each before making a decision.
Understanding Policy Features and Benefits
When comparing life insurance policies, it's crucial to look beyond the surface to understand the policy features and benefits that can provide additional security. These features, often referred to as riders, can significantly enhance the value of a policy. For instance, an accelerated death benefit allows for early payout under certain conditions, while a waiver of premium ensures your coverage continues even if you become disabled and unable to pay premiums.
Policy Features and Riders:
Accelerated death benefits
Waiver of premium
Guaranteed insurability options
It's essential to know the details of how life insurance works, as the right features can transform a policy from a simple contract into a dynamic part of your financial safety net.
Understanding the implications of policy stipulations is just as important as the benefits. Questions should be asked to clarify how the policy functions in various scenarios, such as filing a claim or adjusting to life changes. Additionally, be aware of policy exceptions and exclusions, as they can critically impact the effectiveness of your coverage.
How to Read and Compare Policy Quotes
When venturing into the realm of life insurance, understanding how to effectively read and compare policy quotes is crucial. Begin by gathering quotes from several insurers, ensuring that each quote is based on the same policy type, coverage amount, and personal information. This standardization allows for an apples-to-apples comparison, giving you a clearer picture of the value each policy offers.
It's essential to delve beyond the surface numbers and scrutinize the finer details of each policy. Consider the implications of policy stipulations on your daily life and future financial planning. Ask pointed questions to gain a transparent understanding of how the policy functions in the event of a claim and how it aligns with your changing needs.
To aid in this comparison, a structured approach can be helpful. Here's a simple checklist to keep in mind:
Confirm that the coverage amounts are identical.
Check the term length for term insurance policies.
Evaluate the premium costs, but also the benefits and exclusions.
Review the financial stability and ratings of the insurance providers.
Consider the customer service reputation and claims process of each company.
Choosing the Right Life Insurance Provider
Researching Insurance Companies
When selecting a life insurance provider, it's crucial to conduct thorough research to ensure that your family's future is in reliable hands. Start by investigating the insurer's financial stability; this is a non-negotiable aspect as it reflects the company's ability to honor claims over time. Established agencies such as A.M. Best or Standard & Poor's provide credit ratings and financial statements that are indispensable in this evaluation.
Next, delve into customer satisfaction ratings and seek out testimonials and third-party reviews. These insights offer a glimpse into the insurer's track record with clients and can highlight the experiences of other policyholders. It's important to partner with a company that not only fits your coverage needs but also upholds a reputation of integrity and responsiveness.
Remember, the choice of an insurance company is as significant as the policy itself. The right provider should be a pillar of trust, demonstrating a consistent track record of reliability and fiscal responsibility.
Lastly, consider the resources available for ongoing education and analysis of insurance issues. Organizations like the Center for Insurance Policy and Research - NAIC play a pivotal role in driving dialogue and action on current insurance matters.
Evaluating Customer Service and Claims Process
When selecting a life insurance provider, assessing the quality of customer service and the claims process is crucial. This involves considering how accessible and responsive the insurer is, as well as the efficiency and transparency of their claims processing. Customer reviews and testimonials can provide valuable insights into the satisfaction of current policyholders.
Understanding the claims process is essential. Familiarize yourself with the necessary steps, required documents, and expected response times to prevent delays during stressful times.
It's important to treat each review and testimonial as a significant indicator of the insurer's reliability. Real-life experiences can reveal how the company performs when it matters most. Additionally, examining customer satisfaction ratings can give you a clear view of the insurer's service quality and claims handling.
Checking Financial Stability and Ratings
When selecting a life insurance provider, checking their financial stability and ratings is crucial. These ratings are a reflection of the insurer's ability to meet its financial obligations and are indicative of its overall health and longevity. Agencies such as A.M. Best or Standard & Poor's provide these ratings based on a comprehensive analysis of the insurer's financial strength, performance, and market position.
It's essential to review an insurer's long-term financial statements and credit ratings to gauge their resilience against market fluctuations and their capability to honor claims.
For a quick reference, here's a simplified table showing how ratings can be interpreted:
Rating Agency
Rating
Interpretation
A.M. Best
A++
Superior
A.M. Best
A
Excellent
JD Power
881
High Satisfaction
Remember, a high customer satisfaction rating often correlates with a company's efficiency in handling claims and addressing client concerns.
Maintaining and Reviewing Your Life Insurance
Updating Your Policy to Reflect Life Changes
Life insurance is a dynamic commitment that should evolve as your life does. Significant life events such as marriage, the birth of a child, or a change in financial status necessitate a policy review and update. It's crucial to ensure that your coverage amounts and beneficiary designations are in sync with your current circumstances.
Review beneficiary designations to reflect current relationships.
Adjust coverage amounts to align with new financial responsibilities.
Consider the impact of career changes on your insurance needs.
Regularly monitoring the performance of your policy, including any cash value growth or investment returns, is essential to maintain its effectiveness over time. This vigilance helps in keeping the policy aligned with both evolving needs and budgetary constraints.
Remember, life insurance is not a static purchase; it's a protection plan that should be revisited periodically. Whether it's due to personal milestones or changes in your financial landscape, updating your policy is a proactive step towards ensuring your family's security.
The Importance of Regular Policy Reviews
Life insurance is a dynamic commitment that requires ongoing attention to ensure it remains in sync with your life's evolution. Regular policy reviews are crucial to maintaining a safety net that adapts to your changing circumstances. These reviews allow you to adjust coverage, premiums, and benefits to fit new life milestones such as marriage, the birth of a child, or purchasing a home.
Review your policy in the context of major life events.
Assess the balance between premium costs and the coverage benefits.
Scrutinize policy exceptions to avoid uncovered risks.
Vigilance in policy review is not just about keeping premiums in check; it's about ensuring that your coverage continues to align with your family's needs and your financial goals.
By engaging with your insurance provider and reevaluating your policy periodically, you can protect your family's future and create a lasting legacy. It's not just about the possibility of large debts or financial support after death; it's about the peace of mind that comes from knowing your loved ones are protected.
When to Consider Increasing or Decreasing Coverage
Life insurance is not a static entity; it should evolve with your life's journey. Regular reviews of your policy are crucial to ensure that your coverage aligns with your current needs and life circumstances. Significant life events such as marriage, the birth of a child, or the purchase of a home may necessitate an increase in coverage to provide adequate protection for your growing responsibilities.
Conversely, there may be times when decreasing your coverage is appropriate. As children grow up and become independent, or a mortgage is paid off, your financial obligations may diminish. This could be an opportunity to lower your premiums while still maintaining a safety net.
It's essential to strike a balance between being over-insured, which can unnecessarily strain your finances, and being under-insured, which can leave your family vulnerable. Evaluating your coverage periodically allows you to make informed decisions about adjusting your policy.
Remember to consider the potential impact of reducing coverage. By reassessing your coverage needs, you can ensure that your policy continues to meet your financial goals without leaving gaps in protection or paying for unnecessary coverage.
Conclusion
In conclusion, securing the right life insurance policy is a pivotal decision that safeguards your family's financial future. Throughout this guide, we've explored the importance of aligning a policy with your personal goals, understanding the various types of insurance available, and the significance of thorough research. Remember, life insurance is not a one-size-fits-all solution; it requires careful consideration of your unique circumstances and needs. By following the steps outlined, you can confidently navigate the market to find a policy that offers peace of mind and stability for your loved ones. Keep in mind that life is ever-changing, and so should your coverage. Regularly reviewing and adjusting your life insurance ensures that it remains in step with your life's journey. Invest the time now to make an informed choice, and you'll provide a lasting legacy of security for those you cherish most.
Frequently Asked Questions
What are the main types of life insurance policies available?
The main types of life insurance policies include term life insurance, which provides coverage for a specific period, and permanent life insurance, such as whole life and universal life, which offer lifelong coverage and may include a cash value component.
How do I determine the right amount of life insurance coverage for my family?
To determine the right coverage amount, consider your financial obligations, future goals, income replacement needs, and any debts or expenses your family would need to cover in the event of your passing. A financial advisor can help you calculate a suitable amount.
What factors should I consider when choosing a life insurance provider?
When choosing a provider, research the company's reputation, financial stability, customer service record, and claims process. Look for ratings from independent agencies and read reviews from current policyholders.
How often should I review my life insurance policy?
It's recommended to review your life insurance policy at least every few years or after major life events such as marriage, divorce, the birth of a child, or a significant change in financial circumstances to ensure your coverage remains adequate.
Can I change my life insurance policy if my needs change?
Yes, many life insurance policies allow for adjustments. You may be able to increase or decrease coverage, change beneficiaries, or even convert a term policy to a permanent one, depending on the terms of your policy.
Is life insurance necessary at every stage of life?
Life insurance needs can vary depending on your life stage and financial responsibilities. While it's commonly sought after by those with dependents or significant debts, even individuals without dependents may benefit from life insurance to cover end-of-life expenses or leave a legacy.
Life insurance is a crucial component of financial planning, offering not only protection for loved ones in the event of one's passing but also, in some cases, a savings component known as cash value. Understanding cash value in life insurance policies is essential for policyholders who want to maximize their financial strategy. This article demystifies the concept of cash value, examining its accumulation, benefits, risks, and the various ways it can be accessed and utilized within permanent life insurance policies.
Key Takeaways
Cash value is a unique feature of permanent life insurance policies, serving as a savings component that grows tax-deferred over time.
Premium payments in cash value policies are allocated to both the insurance cost and the savings component, enabling the cash value to accumulate.
Policyholders can access their cash value through withdrawals, loans, or policy surrender, each with distinct tax implications and financial consequences.
While cash value can offer financial flexibility and growth, it also comes with potential risks and costs that must be carefully evaluated.
Consulting with financial experts and comparing different cash value life insurance products can help individuals make informed decisions that align with their financial goals.
The Basics of Cash Value in Life Insurance
Defining Cash Value and Its Role in Permanent Policies
Cash value is a distinctive feature of permanent life insurance policies, serving as a financial reservoir that policyholders can tap into under certain conditions. It represents the savings component of a policy that accumulates value over time. This cash value grows tax-deferred, meaning taxes on the interest or investment gains are not paid until the money is withdrawn.
The role of cash value in permanent policies is multifaceted:
It can be used to pay premiums, effectively lowering the out-of-pocket cost for the insurance.
Policyholders may borrow against the cash value for loans, which can be used for various personal expenses.
In some cases, it can serve as an additional source of retirement income or fund long-term care needs.
While cash value adds a layer of financial utility to life insurance, it's important to weigh the benefits against the costs and potential impact on the death benefit.
Understanding the implications of cash value is crucial for policyholders, as it affects both the present financial flexibility and future benefits of the life insurance policy.
Types of Life Insurance Policies with Cash Value Features
Life insurance policies with cash value features are distinct from term life insurance, which lacks this component. Whole life, universal life, and variable life insurance are the primary types of permanent policies that include a cash value feature. Each type offers unique approaches to premium payments and cash value growth.
Whole life insurance guarantees a fixed premium and a cash value that grows at a predetermined rate.
Universal life insurance provides more flexibility with premium payments and cash value growth based on market interest rates.
Variable life insurance allows policyholders to invest the cash value in various investment options, which can lead to higher growth potential but also comes with increased risk.
Cash value is a crucial aspect of permanent life insurance, enabling policyholders to accumulate a tax-deferred balance that can be accessed during their lifetime. It's important to understand that in the early years, cash value growth is typically slow, but it accelerates over time, potentially offering a higher return.
Comparing Cash Value to the Death Benefit
Understanding the distinction between cash value and the death benefit is crucial in evaluating life insurance policies. The death benefit is the amount paid to beneficiaries upon the policyholder's death, while the cash value serves as a savings component that can be accessed during the policyholder's lifetime.
The cash value is not intended for beneficiaries and typically reverts back to the insurance company upon the policyholder's death. However, certain policies may offer both the death benefit and cash value, but at a higher cost.
Cash value can be utilized in various ways, such as reducing premium payments, supplementing retirement income, or covering unexpected expenses. It's important to note that the method of cash value payout can differ based on the type of policy. For instance, universal life policies may allow the cash value to be paid out as part of, or in addition to, the death benefit.
Mechanics of Cash Value Accumulation
How Premium Payments Contribute to Cash Value
When you purchase a cash value life insurance policy, your premium payments are allocated in several ways. A portion of each premium contributes directly to the cash value, which grows over time. This growth is tax-deferred, meaning you won't pay taxes on the gains as they accrue.
The allocation of premium payments can be broken down as follows:
Policy fees and charges
The cost of the insurance coverage
The cash value account
Depending on the type of policy, the cash value may earn a fixed interest rate or vary with market performance. It's essential to recognize that not all of your premium goes into the cash value; a significant part covers the insurance and associated fees.
Accessing the cash value can be done through withdrawals or loans, but these actions may affect the policy's benefits and the death benefit amount. It's crucial to understand the terms and potential consequences before utilizing the cash value.
The Impact of Interest and Investment on Cash Value Growth
The growth of cash value in a life insurance policy is significantly influenced by the interest rate or investment performance. Policies with a fixed interest rate provide a steady, predictable increase in cash value over time. In contrast, policies tied to investment performance can see more variable growth, often reflecting market conditions.
Your policy's interest rate or investment choices determine the rate of cash value accumulation.
Market-linked policies may have a minimum guaranteed return (floor) and a maximum growth cap (ceiling).
Comparatively, direct investments in stocks or mutual funds may offer higher returns but come with increased risk.
The balance between stability and potential for growth is a key consideration when evaluating the suitability of cash value life insurance as an investment.
It's important to understand that while some policies guarantee a minimum rate of return, others allow for participation in potentially higher gains from market performance, albeit with a ceiling to limit maximum growth. This structure aims to provide a level of protection against market volatility while offering the opportunity for cash value appreciation.
Understanding Policy Loans and Withdrawals
Policyholders have the flexibility to access their policy's cash value through loans and withdrawals, each with its own set of implications. Withdrawals reduce the death benefit by the amount taken out, as they are a direct removal of funds from the policy's cash value. This can be advantageous for immediate financial needs or significant life events, like purchasing a home.
Loans, on the other hand, allow policyholders to borrow against their cash value. These loans typically do not require a credit check and may offer lower interest rates compared to traditional loans. While not mandatory, repaying the loan is beneficial to maintain the policy's full death benefit. Failure to repay can result in a reduced death benefit, as the outstanding loan amount plus interest will be deducted.
The strategic use of policy loans and withdrawals can enhance the utility of a life insurance policy, making it a dynamic financial instrument.
It's crucial to understand the tax implications of these actions. Withdrawals are generally tax-free up to the amount of premiums paid, but loans are not considered taxable income. However, if the policy lapses with an outstanding loan, the amount exceeding the premiums paid may be taxed as income.
Advantages and Drawbacks of Cash Value Policies
The Financial Benefits of Building Cash Value
Building cash value within a life insurance policy offers a unique blend of financial security and wealth accumulation. The cash value acts as a savings component, growing over time and providing a range of benefits that extend beyond the traditional death benefit. Here are some of the key financial advantages:
Tax-deferred growth: The cash value in your policy grows without immediate tax implications, allowing your investment to compound more efficiently over time.
Loan collateral: You can borrow against the cash value of your policy, often at favorable interest rates, without disrupting the policy's death benefit.
Flexible use of funds: Access to cash value can provide financial support for various needs, such as supplementing retirement income or covering unexpected expenses.
The strategic use of cash value can significantly enhance your financial planning, offering a versatile tool for managing both present and future financial challenges.
It's important to note that while the benefits are substantial, they must be balanced against the costs and risks associated with cash value policies. Careful consideration and planning are essential to ensure that a cash value life insurance policy aligns with your long-term financial objectives.
Potential Risks and Costs Associated with Cash Value
While cash value life insurance offers a savings component and the potential for growth, it's important to be aware of the risks and costs involved. Policies with cash value are generally more expensive than term life insurance, as a portion of your premium goes towards building the cash value.
Interest and tax complications: Loans against the cash value may incur interest and create potential tax liabilities.
Reduced death benefit: Taking out loans against the policy can reduce the death benefit available to beneficiaries.
Growth takes time: Building a significant cash value can take many years, and early withdrawals may have financial penalties.
It's crucial to consider these factors in the context of your overall financial plan and to consult with a financial advisor to determine if a cash value policy aligns with your goals.
Evaluating the Suitability of Cash Value Life Insurance for Your Financial Goals
When considering cash value life insurance, it's essential to assess how well it aligns with your financial objectives. This type of policy combines a death benefit with a savings component, allowing the cash value to grow over time. Here are some factors to consider:
Long-term financial goals: Is building a tax-deferred savings account for retirement or future expenses important to you?
Financial flexibility: Do you value the option to borrow against the policy or make withdrawals during your lifetime?
Costs versus benefits: Are the potential growth and the financial benefits worth the typically higher premiums compared to term life insurance?
It's crucial to understand that cash value life insurance is not merely an expense but an investment in your future financial security. However, it's not suitable for everyone, and the decision should be based on a thorough analysis of your individual circumstances.
Before making a decision, consider speaking with a financial advisor to determine if a cash value policy makes sense for you. They can help you weigh the pros and cons, taking into account your unique financial situation and goals.
Accessing Your Policy's Cash Value
Options for Withdrawing Cash Value
Policyholders have several avenues to access the cash value of their life insurance policies. Withdrawing funds directly is a straightforward method, allowing you to use the cash for any purpose, from emergency expenses to planned investments like a home down payment. However, it's crucial to remember that such withdrawals can reduce the remaining death benefit.
Another common option is to take out a loan against the cash value. This approach provides liquidity without an immediate reduction in the death benefit, but it does come with the obligation to repay the loan with interest. Failure to repay can lead to a decrease in the death benefit or policy lapse.
Policyholders may also use their accumulated cash value to cover premium payments, which can help maintain the policy without out-of-pocket expenses.
Lastly, full or partial surrender of the policy is possible, though this often comes with tax implications, especially if the withdrawal amount exceeds the premiums paid.
The Tax Implications of Accessing Cash Value
When you access the cash value of your life insurance policy, the tax implications can vary based on the method and amount you withdraw. Withdrawals up to the amount of premiums paid are generally not taxable. However, amounts exceeding the premiums paid are subject to income tax.
Scenario 3: Withdrawing partially or fully may result in taxes on the excess over premiums paid.
Scenario 4: Using cash value to pay premiums is typically not taxable.
The cash value in a life insurance policy grows tax-deferred, meaning you won't owe taxes on the growth until you withdraw the funds. It's crucial to understand that policy loans and withdrawals reduce the death benefit and may take a considerable time to build up, potentially affecting the long-term value of your policy.
Strategies for Maximizing Your Policy's Cash Value Potential
To enhance the growth of your policy's cash value, consider these strategies:
Regularly review your policy's performance to ensure it aligns with your financial goals. Adjust your investment choices in variable policies to respond to market conditions and optimize returns.
Reinvest dividends back into your policy to increase the cash value.
Use the cash value to pay premiums, which can help sustain the policy and continue its growth without out-of-pocket expenses.
By strategically managing your policy, you can leverage the cash value as a tool for wealth building and financial planning.
Remember, the cash value of your policy can serve multiple purposes. It can be used to supplement retirement income, cover long-term care costs, or even reduce your premium payments. The key is to balance the use of cash value with the preservation of the death benefit for your beneficiaries.
Making an Informed Decision on Cash Value Life Insurance
How to Assess Different Cash Value Life Insurance Products
When evaluating cash value life insurance products, it's crucial to understand the nuances that differentiate one policy from another. Consider the policy's flexibility, such as the ability to adjust premium payments and the ease of accessing cash value. Assess the investment component, which can significantly influence the growth of the cash value over time.
Review the types of policies available: whole life, universal life, and variable life insurance.
Compare the interest rates or investment returns each policy offers.
Examine the fee structure, including premiums, administrative fees, and potential penalties for early withdrawal.
It's essential to align the policy's features with your long-term financial objectives, ensuring it complements your overall financial plan.
Finally, scrutinize the insurer's financial strength and reputation, as this will impact the security of your investment. Policies should be compared not just on their projected cash value growth, but also on the company's track record of reliability and customer service.
Consulting with Financial Experts on Cash Value Benefits
When considering cash value life insurance, consulting with financial experts can provide clarity and confidence in your decision. Experts can tailor advice to your unique financial situation, ensuring that the policy aligns with your long-term goals and investment strategy. They can help you understand complex policy details, such as fees, surrender charges, and the implications of loans and withdrawals on your policy's value.
Evaluate your financial goals and needs
Analyze the long-term performance of different cash value policies
Consider tax implications and potential risks
Develop a strategy for integrating the policy with your overall financial plan
Financial experts can offer insights into how cash value life insurance fits into a diversified portfolio and its role in estate planning. Their guidance is invaluable in navigating the nuances of these policies and in making an informed decision that benefits your financial future.
Real-life Examples and Case Studies of Cash Value Utilization
Understanding how cash value in life insurance works in real-life scenarios can provide valuable insights into its practical benefits and applications. Case studies often reveal the versatility of cash value, demonstrating how individuals can use it to address various financial needs throughout their lifetimes.
John Doe, at age 45, borrowed against his policy's cash value to fund his child's college education, avoiding the need for student loans.
Jane Smith, a retiree, supplemented her income by making systematic withdrawals from her policy's cash value, thus maintaining her lifestyle without depleting other retirement savings.
The Johnson Family Trust utilized the cash value of their policy to settle estate taxes, ensuring a smooth transfer of assets to beneficiaries.
The strategic use of cash value can significantly impact financial planning, offering a flexible tool for managing life's unpredictable expenses.
It's important to note that while accessing cash value can be advantageous, it must be done with a clear understanding of the policy's terms and the potential impact on the death benefit. Professional advice is recommended to navigate these decisions effectively.
Conclusion
In summary, cash value life insurance policies offer a unique combination of death benefit protection and a savings component that accumulates value over time. While these policies can serve as a financial tool for long-term planning, they may not be suitable for everyone. Understanding the intricacies of how cash value accumulates, the types of policies available, and the potential disadvantages is crucial for making an informed decision. If you're considering a cash value life insurance policy, it's important to weigh the benefits against the costs and to consult with a financial advisor to ensure it aligns with your overall financial strategy. For those seeking guidance, our life insurance specialists are available to help you navigate your options and make the choice that best suits your needs.
Frequently Asked Questions
What is cash value in a life insurance policy?
Cash value in a life insurance policy refers to a savings component that is part of permanent life insurance policies. A portion of each premium payment is allocated to this cash value account, where it can earn interest or be invested, growing tax-deferred over time.
How does cash value accumulate in a life insurance policy?
Cash value accumulates in a life insurance policy when a portion of the premium payments is invested by the insurance company into various assets. This can include stocks, bonds, or mutual funds, and the value of these investments grows over time, adding to the policy's cash value.
Can I access the cash value in my life insurance policy?
Yes, policyholders can access the cash value in their life insurance policy through withdrawals, policy loans, or by surrendering the policy. However, accessing the cash value can have tax implications and may reduce the death benefit.
What types of life insurance policies include a cash value feature?
Permanent life insurance policies, such as whole life and universal life insurance, include a cash value feature. This is in contrast to term life insurance, which does not have a cash value component.
Are there any disadvantages to cash value life insurance?
Cash value life insurance policies typically have higher premiums than term life insurance, and accessing the cash value can reduce the death benefit. Additionally, there are fees and potential tax consequences associated with cash value withdrawals or loans.
How do I know if cash value life insurance is right for me?
Determining if cash value life insurance is right for you depends on your financial goals, need for permanent coverage, and desire for a savings component. It's important to consult with a financial advisor to assess your individual situation and consider all potential risks and benefits.